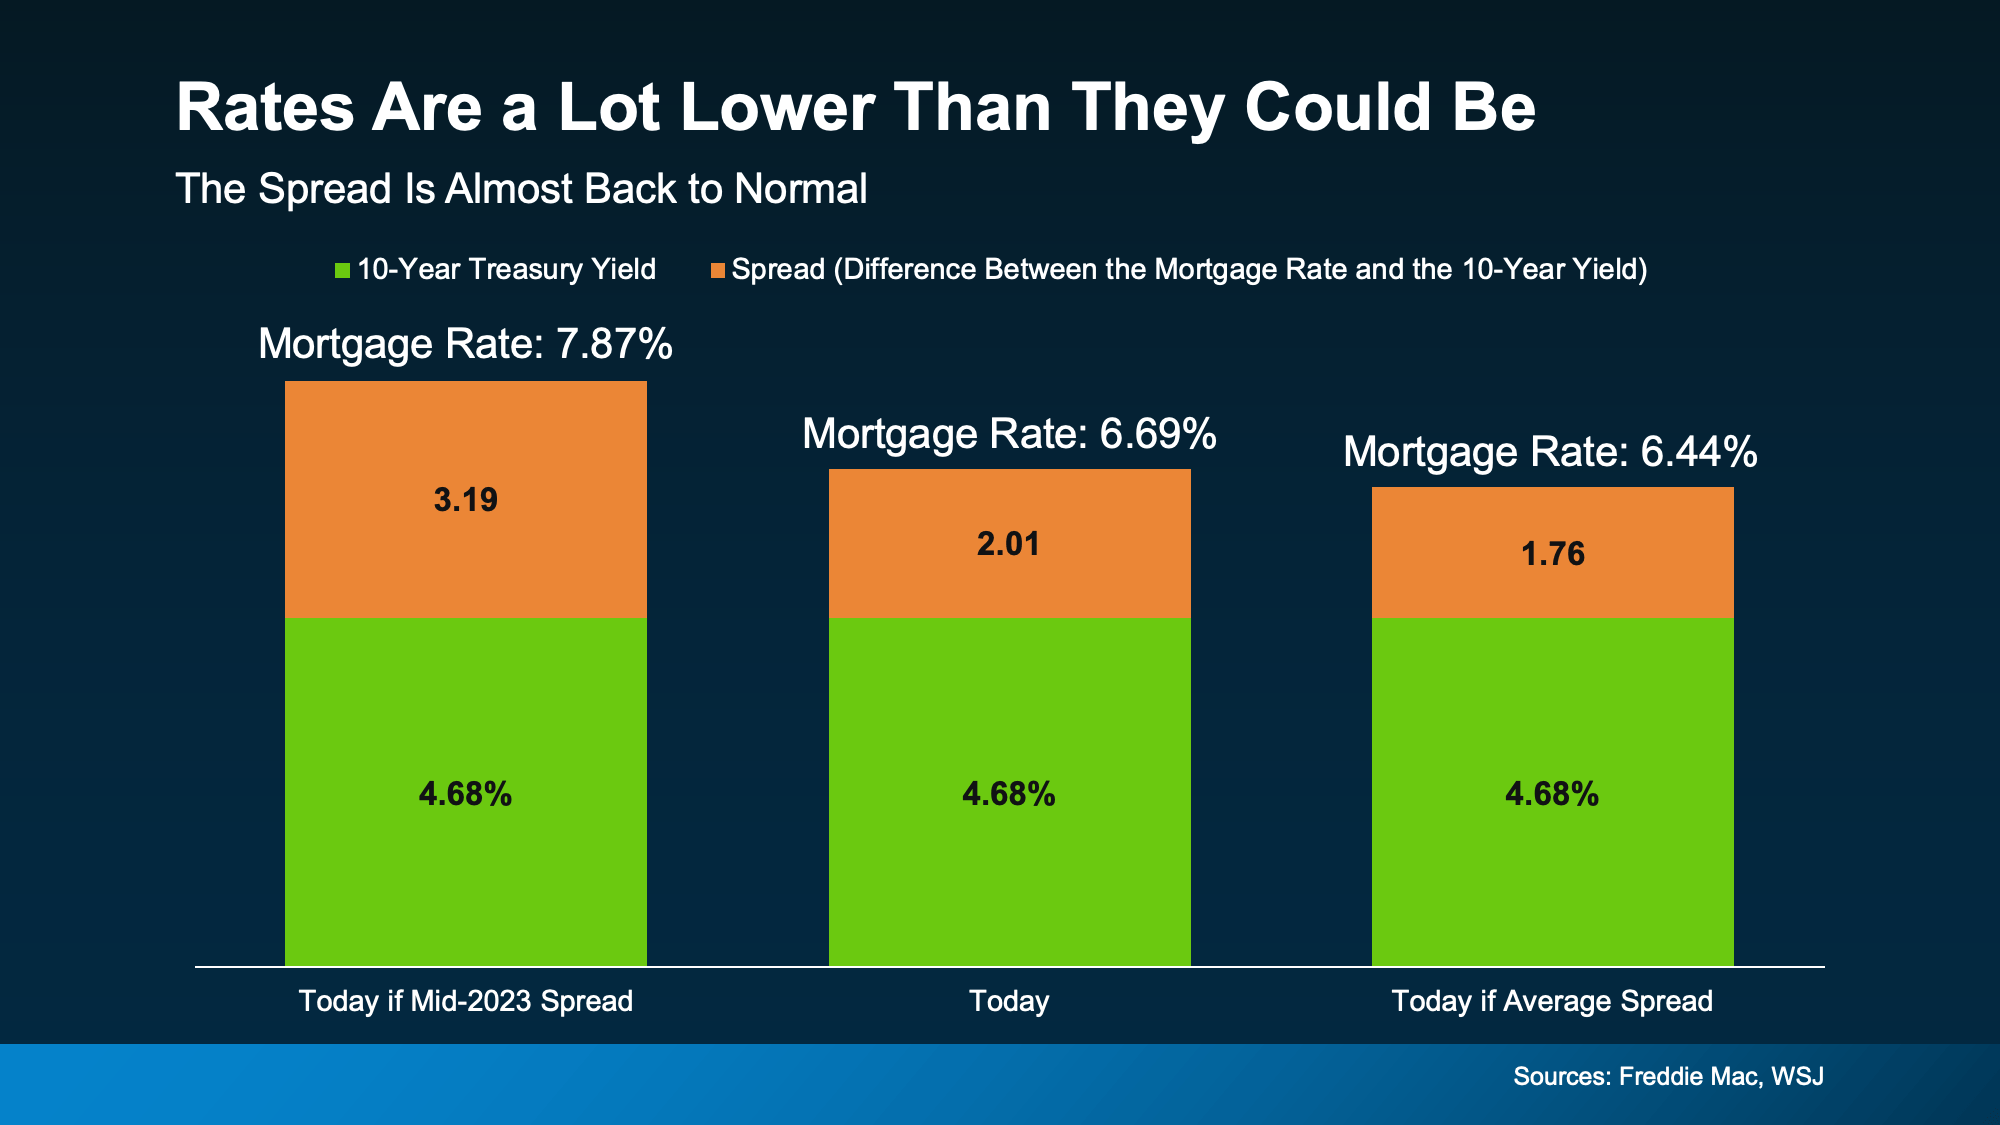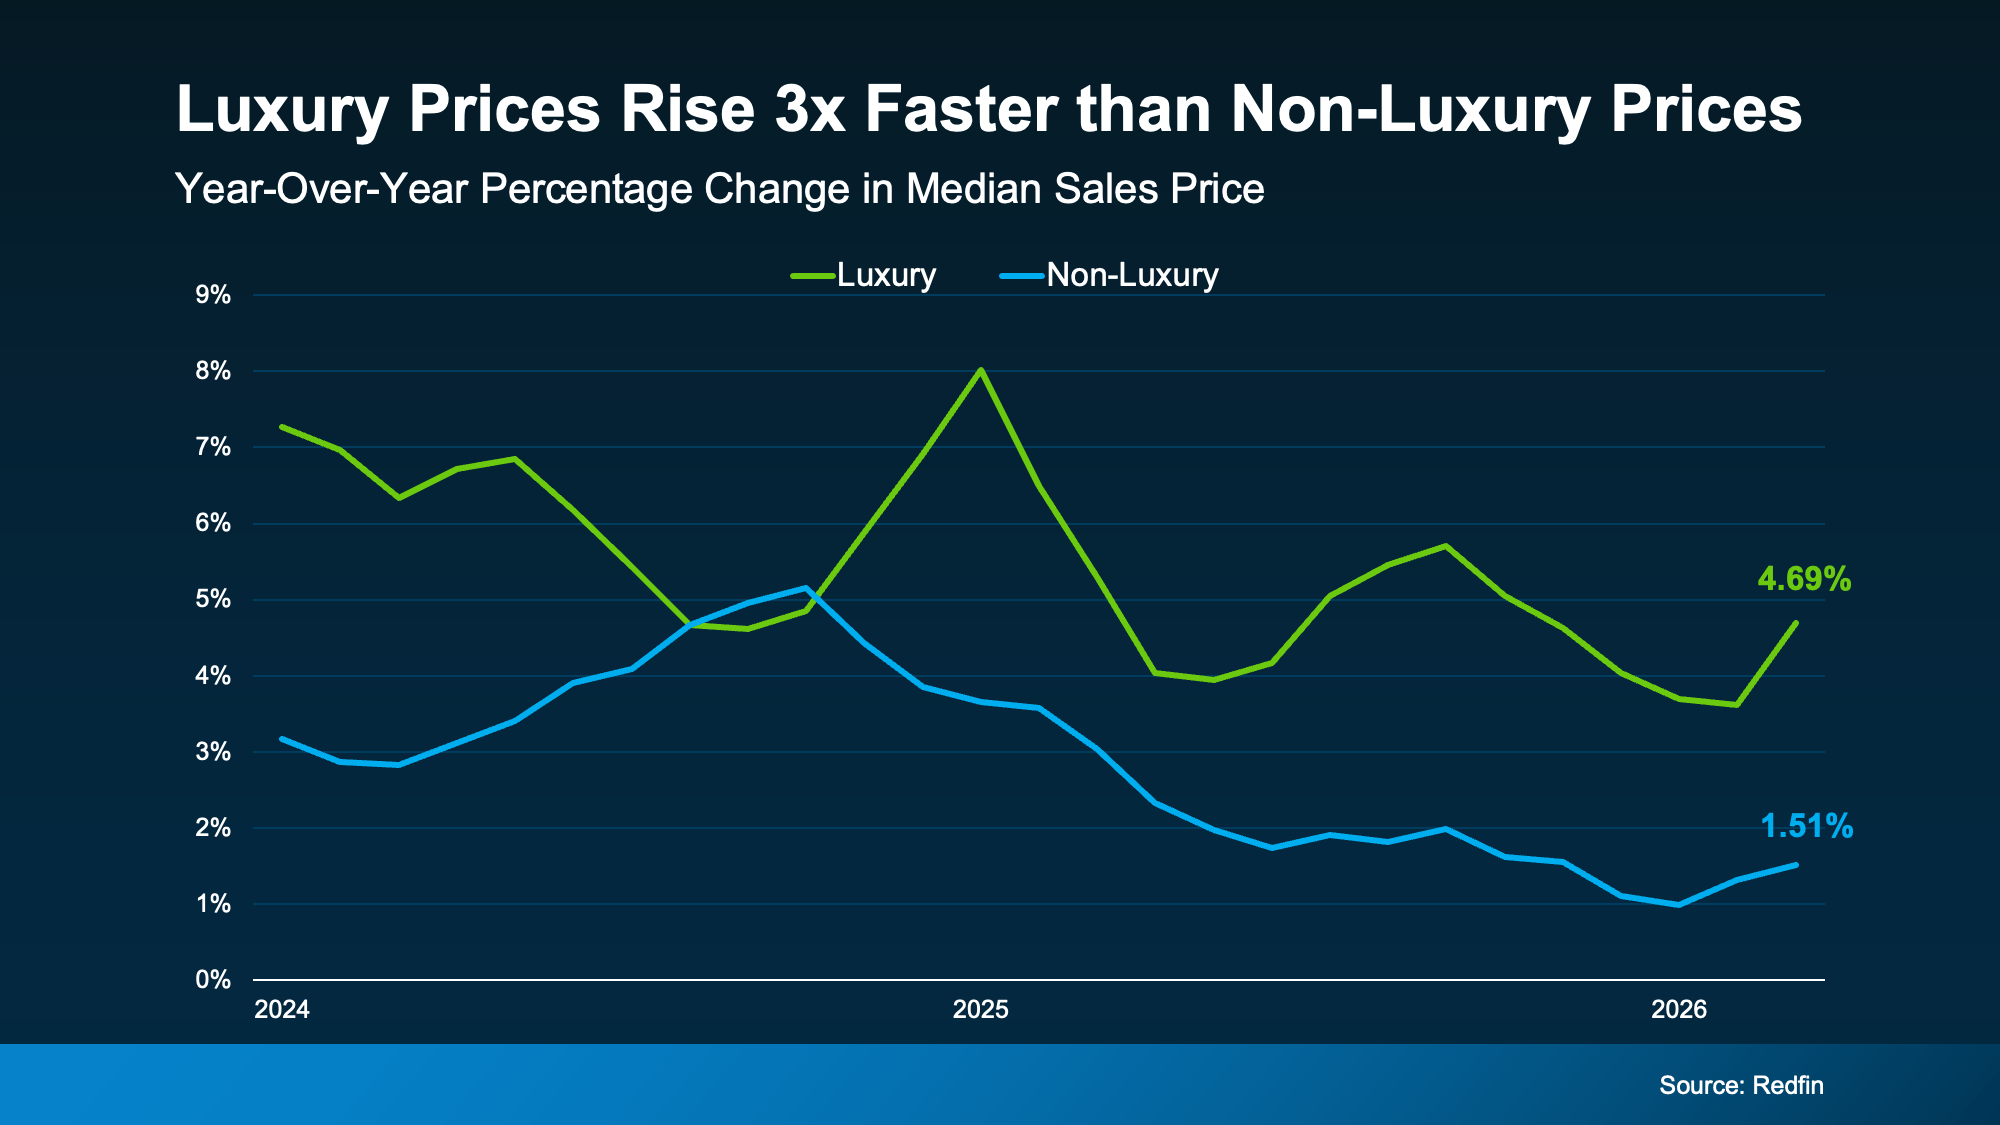Sellers • September 1, 2026

Most Home Sales Close – Here’s How To Keep Yours on Track

Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table.

According to the latest data from Redfin, only about 1 in 7 pending sales are falling through. Meaning the vast majority make it all the way to closing.

And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market.

Why Some Deals Fall Apart Before Closing

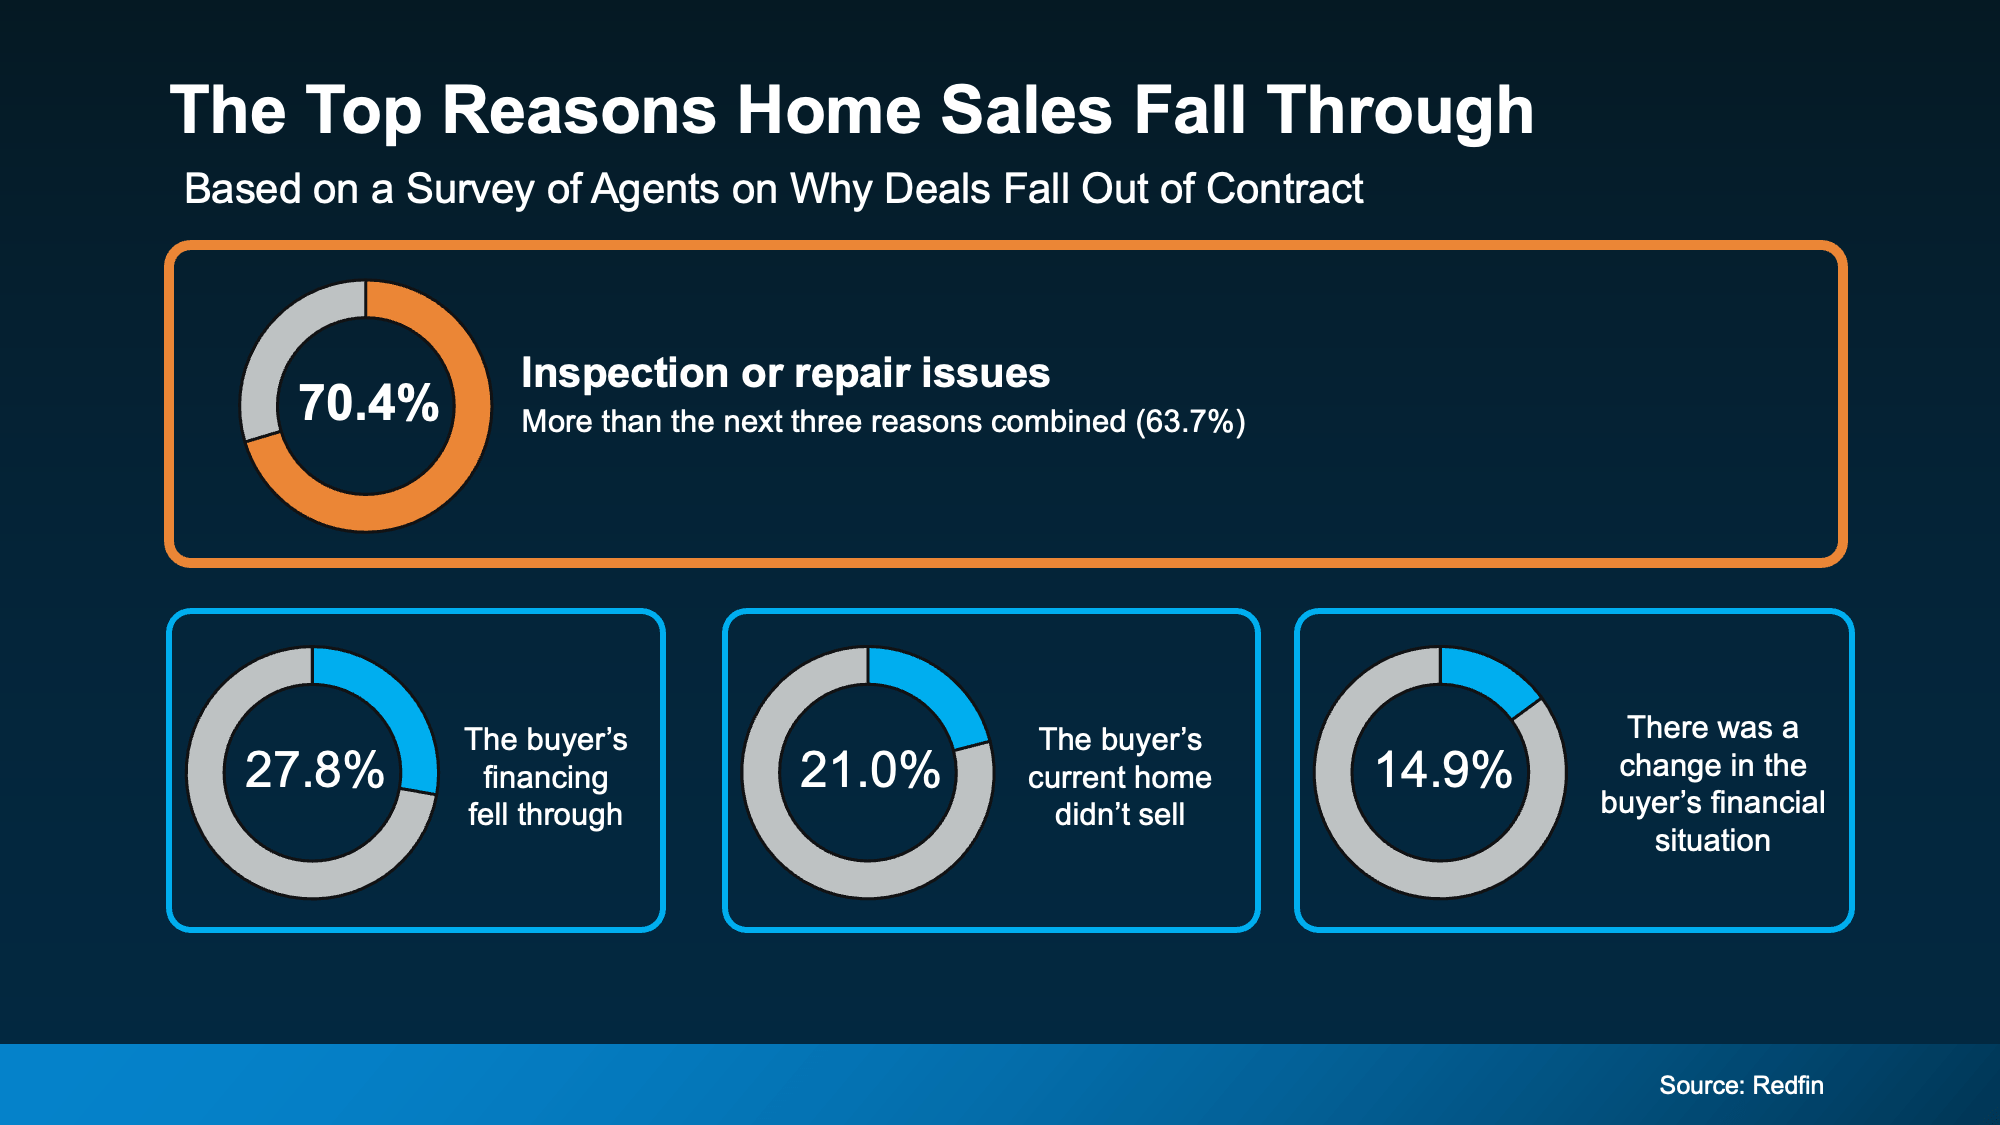
A Redfin survey sheds light on the most common things that trip up a sale (see visual below):
a blue and orange chart with text

Here’s a bit more information on each one.

  • Inspection or repair issues. This is the big one. When a buyer’s inspector finds a problem, whether with the roof, the plumbing, the foundation, or elsewhere, the buyer can push back, ask you to make repairs, request a credit so they can do it themselves, or see if you’ll lower your price. If they don’t get what they want, they may walk away from the deal altogether.
  • The buyer’s financing fell through. Their mortgage loan has to be fully approved in time for closing day. If the loan doesn’t come together, the sale can’t move forward.
  • The buyer’s current house didn’t sell. Some buyers need to sell their own home before they can close on yours. If that takes longer than expected, you may run into some issues with your timeline or even see them give up on their move.
  • There was a change in buyer’s financial situation. A new job, a big purchase, or new debt can change what a buyer qualifies for on their mortgage loan, even after they were pre-approved.

Where Your Agent Makes the Difference

Some of those reasons are outside your control, like whether a buyer’s loan clears or whether they sell their own home in time. But according to Zillow, there are a few proactive things you can do to help make sure your sale goes as smoothly as possible:

  • Save yourself the headache and get a pre-listing inspection. That’s when you get your own inspection before a buyer gets theirs. It lets you find the big issues before a buyer’s inspector does, so you can fix them or disclose them on your terms, instead of scrambling once you’re under contract. In this situation, your agent will help you decide what’s worth addressing and what to just disclose. Handle it now, and the biggest risk to your sale is behind you before a buyer ever brings it up.
  • Look at more than just the offer price. Your agent will help you weigh the whole offer, including the buyer’s timeline and any contingencies attached. When a buyer’s offer depends on selling their own home first, the success of your sale rides on a second deal you can’t see. Sometimes, a slightly lower offer with fewer strings is the safer one. Your agent will help you weigh your options and make a plan that works well for you.

One of those is something you can’t do until you have offers in hand, but the other is something you can get ahead of right now. The pre-listing inspection.

That relatively small cost upfront can save you the much bigger hassle of a deal falling apart later. And while getting your own inspection before listing may not make sense in every market, your agent can tell you whether it’s worth it based on your market, your house, and what buyers are prioritizing in your area.

Sometimes the smartest move is staying one step ahead.

Bottom Line

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish. So, let’s connect and get your house sold.
Sellers • August 31, 2026

One Number Could Change Everything About Your Next Move

When’s the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor’s house sold for. What yours is actually worth right now.

For a lot of homeowners, it’s been years. And if you’ve been thinking about moving, but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number.

Your House May Be Worth More Than You Think

Home values have climbed significantly over the past 5-10 years. And even though today’s market is more balanced, homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast.

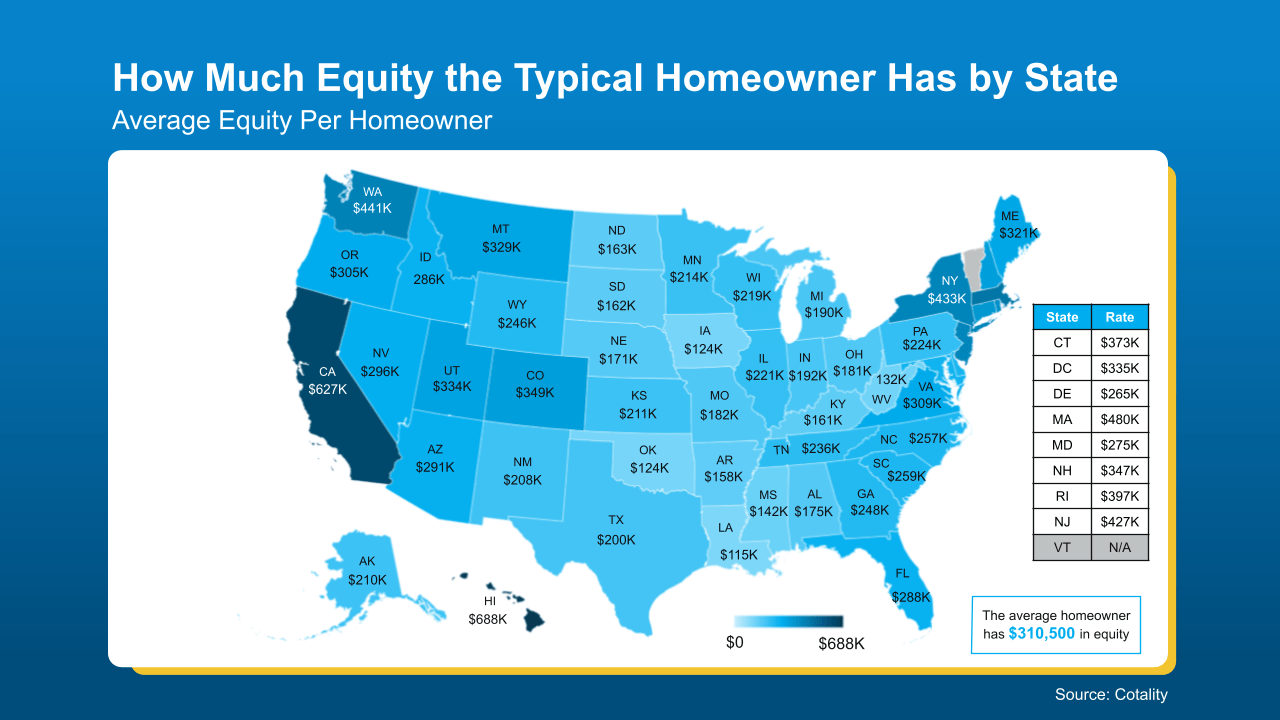
According to Cotality, the typical homeowner with a mortgage now has $310,500 in equity. That’s not a small number. It’s six figures.

And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below):

a map of the united statesEven though every local market is different, the question you should be asking right now is the same: How much equity have you built up?
Because if you don’t know that number, you’re missing out.

This Could Be the Missing Piece in Your Move

Most people assume that because prices are higher and rates aren’t at 3% anymore, moving just isn’t realistic right now, especially if they already have an ultra-low rate. And that’s understandable – those are real factors.

But they’re not the only factors.

When you have that much equity in your house, you’re not starting from scratch. You’re not scraping together a down payment or hoping the numbers work. You’re walking into your next move with more of an advantage than you think. And that changes the math.

What Your Equity Can Do for You

Maybe you’ve outgrown your current house or you’re ready to downsize… The equity you’ve built could help bridge the gap between where you are today and where you want to be next.

Yes, your next house may cost more than your last one did. But your equity could cover a big chunk of that difference. Depending on how much you’ve built, it could help you:

  • Lower your monthly payment on your next home. The bigger your down payment on your next place, the less you have to borrow. And with today’s rates, borrowing less can make a big difference in what you pay every month.
  • Buy your next house with all cash. This surprises a lot of people, but some homeowners have built enough equity to buy their next home outright, in cash. According to the National Association of Realtors, more than one-quarter (26%) of repeat buyers paid all cash for their home in July.
  • Transform the home you already have. Love your neighborhood but not your floor plan? You don’t have to move. Your equity could help fund renovations that make your home fit your life today while potentially adding value for tomorrow.

Your equity doesn’t erase the challenges of the current market. But it does mean you’re walking into your next move with a lot more power and flexibility than you think.

That’s why the value of your home isn’t something you should have to wonder about. 

If you’re even thinking about a move – or if you’re just curious what your options might be – the smartest thing you can do is get a Professional Equity Assessment. It’ll give you a real, market-based evaluation of what your house is really worth right now and how much equity you’re working with.

Because once you see the number, maybe it’s not about whether you can afford to move – it’s about what kind of move makes sense for you.

Bottom Line

If it’s been a while since you’ve gotten a professional look at your home’s value, let’s change that.

Reach out for a free, personalized Home Equity Assessment that estimates what your house could sell for, how much equity you’ve likely built, and what that could mean for your next move.

Buyers • Sellers • August 27, 2026

Higher Rates Could Actually Help Housing Supply – Here’s How.

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

But that may be about to change. Here’s why your pool of options may actually start ticking back up again.

Growth Has Slowed, But It Hasn’t Stopped

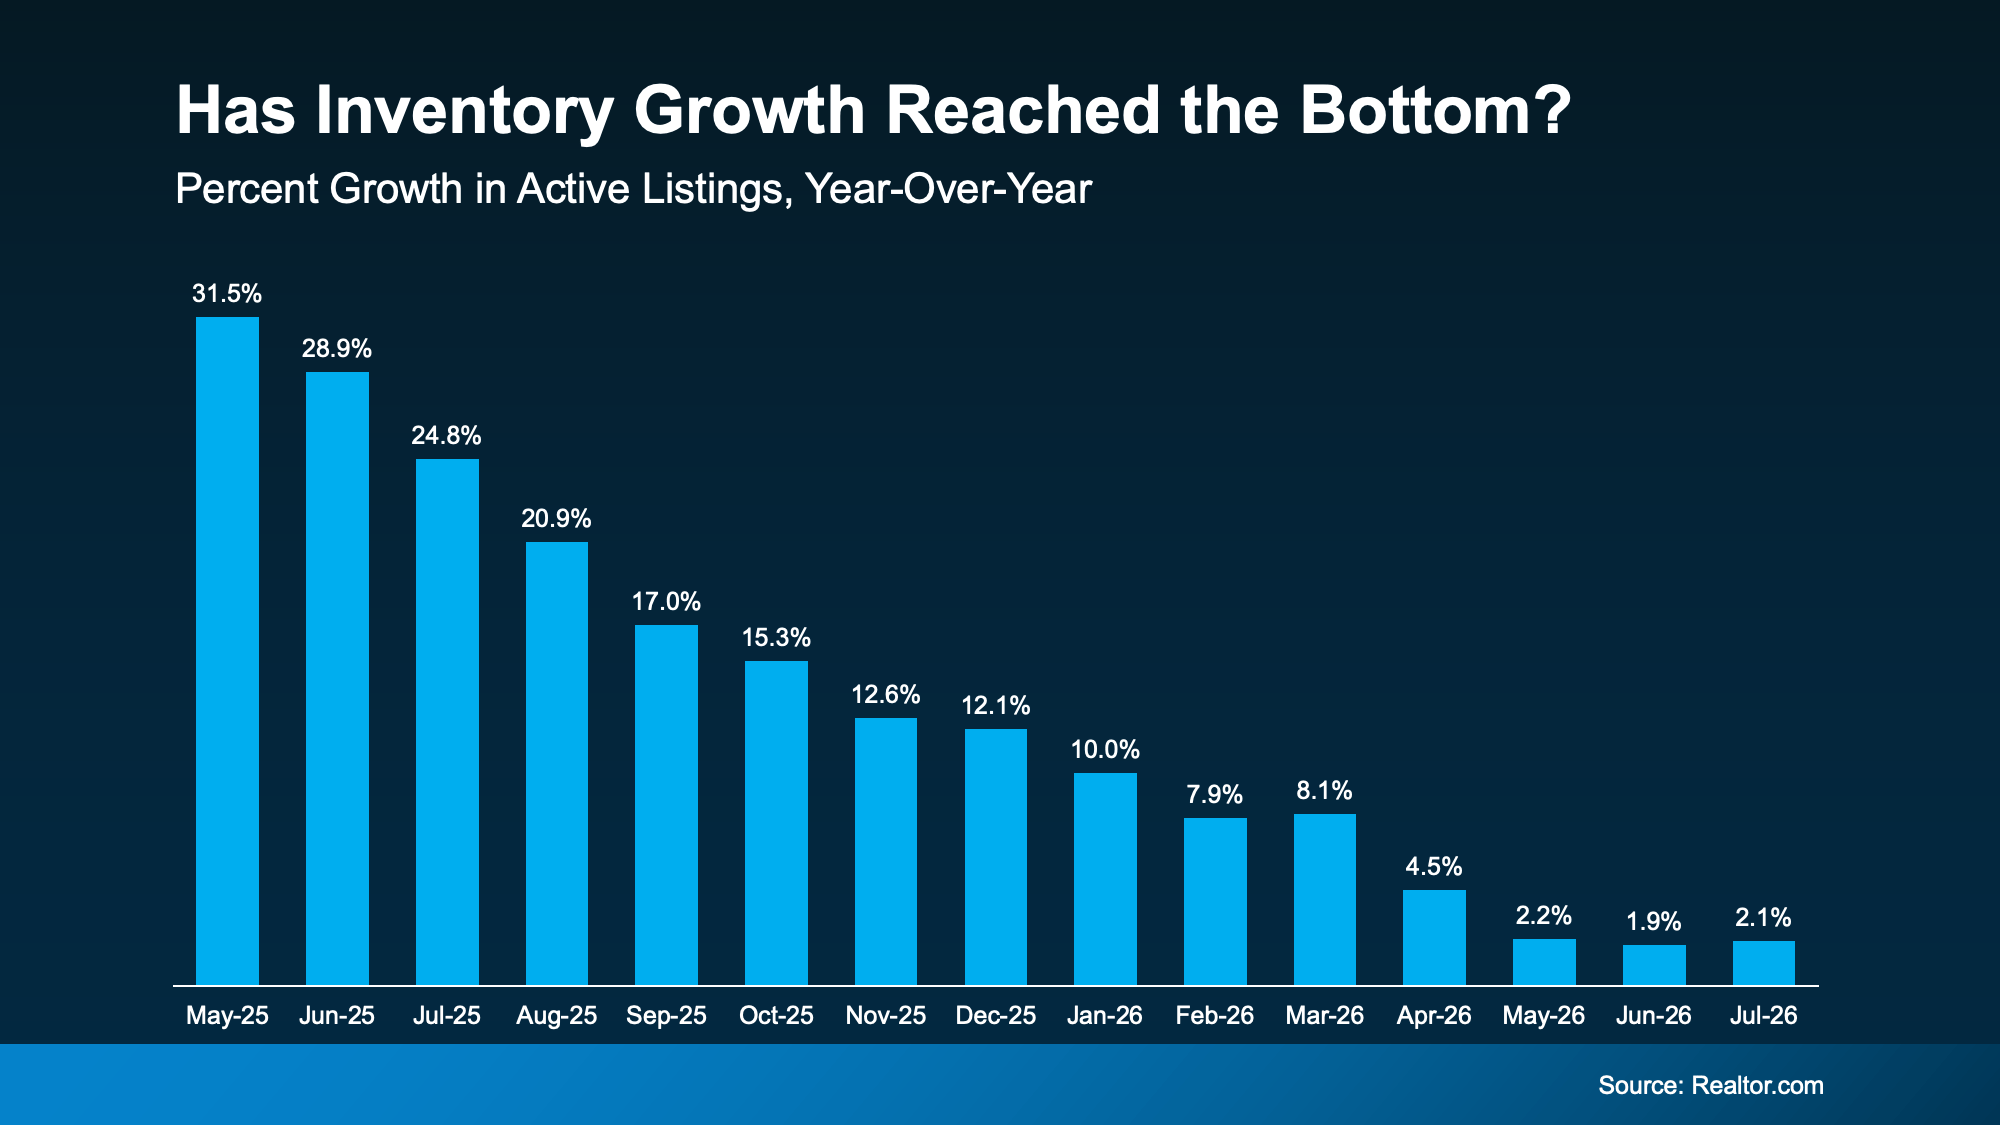
Active listings were up 2.1% year-over-year in July, according to Realtor.com. Back in January, inventory was up 10%. And in May of 2025, it was up 31.5%. So, growth has cooled off a lot over the last year.

The past 3 months, though, have all seen inventory growth land in roughly the same range, which is a sign this slowdown may be nearing its floor (see graph below):

a graph of growth in a blue background

So, what does that mean for you?

Homes are still coming onto the market. Every single one of these bars shows a period where inventory grew. So, don’t be discouraged or let this make you think you’re out of options. Plus, we’ve seen more stability in the numbers lately, which is a good sign.

The Most Homes for Sale Since 2019

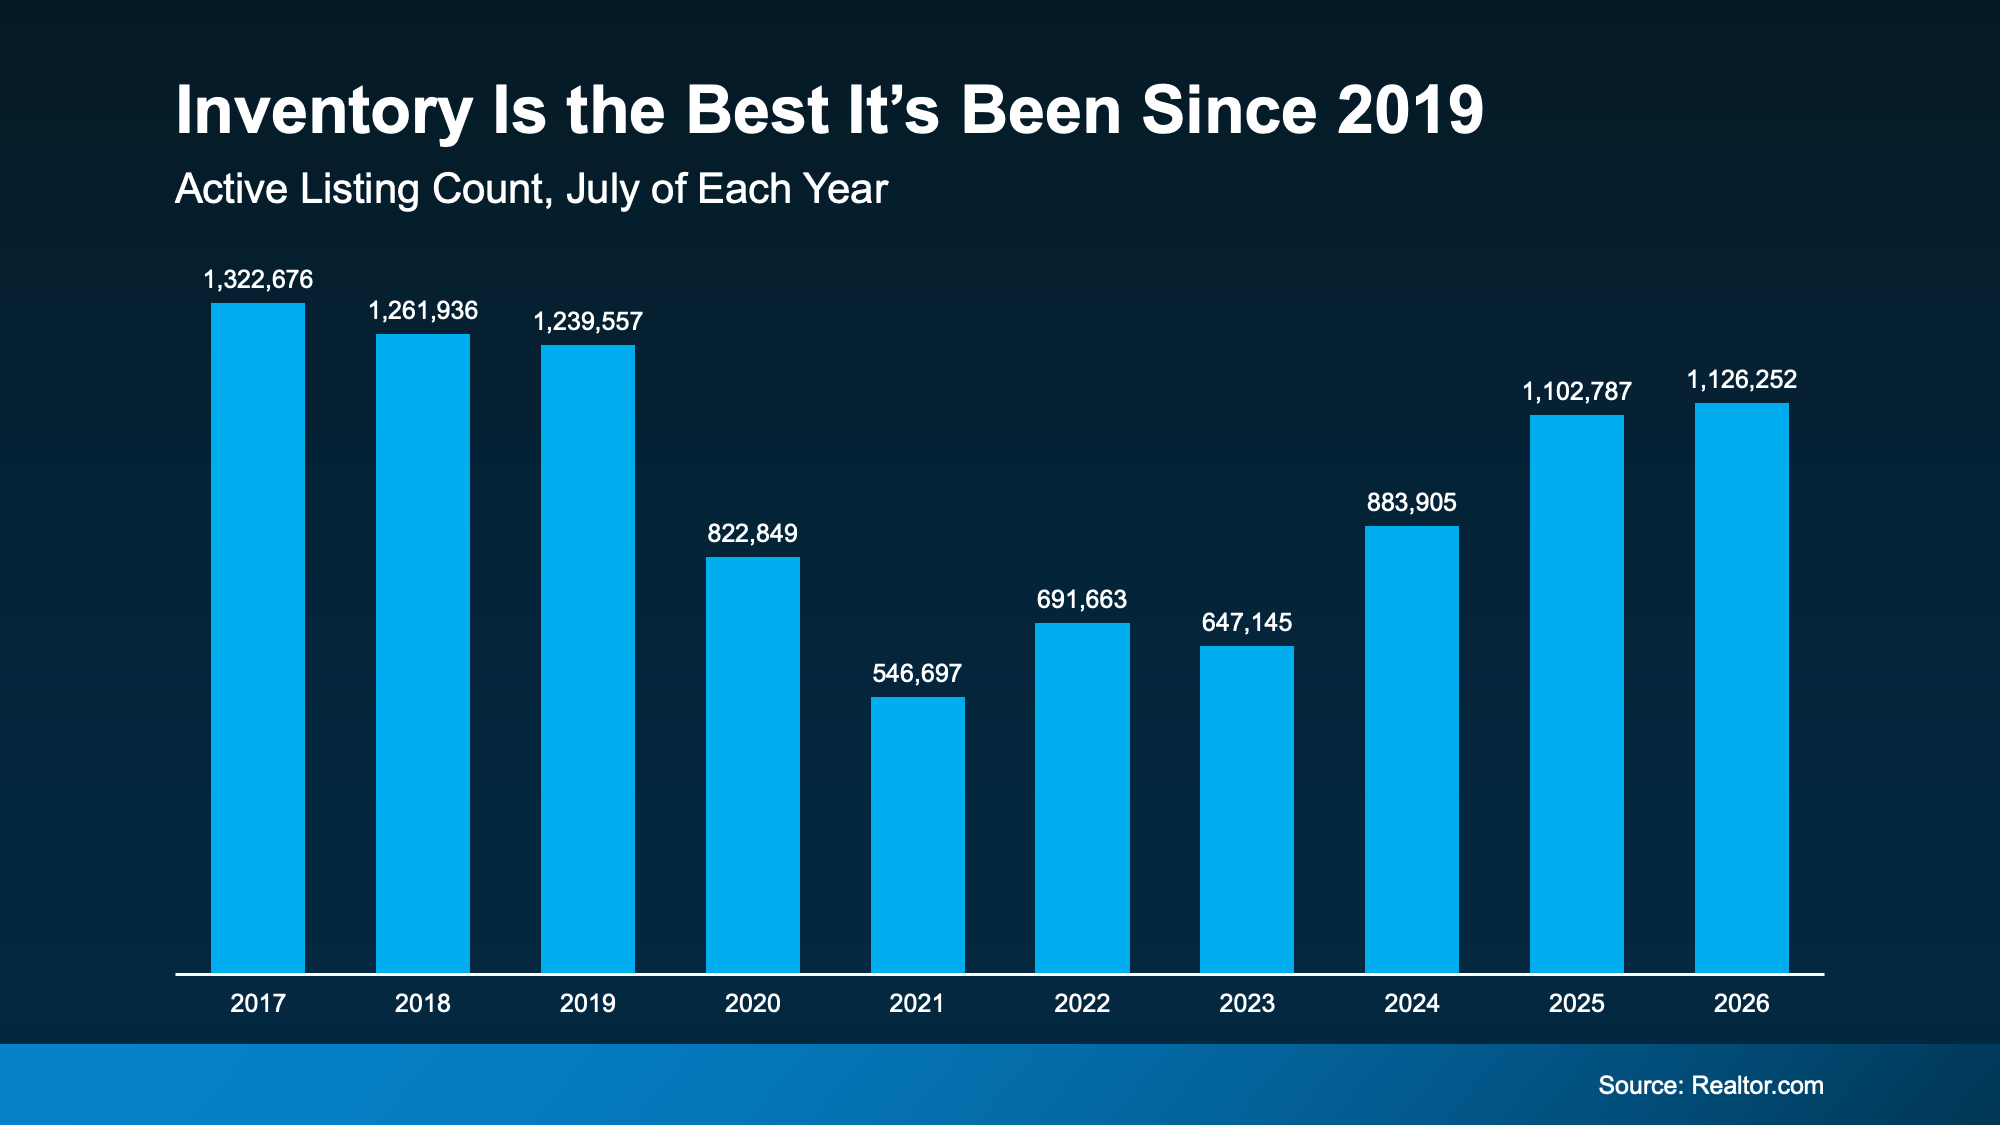
Compared to the rock-bottom lows of 2021, inventory has climbed back substantially. Nationally, the number of homes for sale has been up year-over-year consistently now for 33 months. And inventory has almost doubled in just a few years. So don’t get too hung up on the pace of that increase.

This July was actually the best July for inventory since 2019 (see graph below):

a graph of blue bars with white text

Now, the market still needs about 150k listings to get back to pre-pandemic levels, but things are quickly approaching normal. And experts think we may even be back to 2019 levels by the end of this year, even with the slowdown we’ve already seen.

And that’s thanks to one unlikely factor: mortgage rates.

Why Higher Rates May Actually Help Inventory Grow

It works like this. When mortgage rates climb, inventory tends to climb with them. As Mike Simonsen, Chief Economist at Compass, explains:

“When rates rise; inventory rises. When rates fall; inventory falls. So, from July last year to March this year, rates ease lower and all the inventory growth of the past several years evaporated. If rates move higher from here or stay elevated for [a] longer period of time, then we should expect supply to build again.”

Well, rates are expected to hold in the mid-to-upper 6% range for a while longer, and Realtor.com‘s latest forecast has inventory ending 2026 up 3.6% year-over-year.

That means 2 things:

  • Inventory growth is forecast to pick up a little bit throughout the rest of the year.
  • And, inventory is projected to close the year at a historically normal level, right about where it stood at the end of 2019.

For buyers, that’s a win. Even if today’s rates aren’t your favorite, they’re helping the number of homes on the market to grow. And more homes for sale means more choices, more room to negotiate, and less pressure to rush your search.

Bottom Line

The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in our area? Reach out, and let’s take a look together.

Buyers • Housing Market Updates • Sellers • August 25, 2026

Who Has the Upper Hand in Today’s Housing Market?

Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know if they’ll still get top dollar.

The interesting thing is… both can be right at the exact same time. It just depends on where you live.

That’s because today’s housing market isn’t moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle.

And knowing which market you’re actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down.

One Number Tells You Who’s Got Leverage

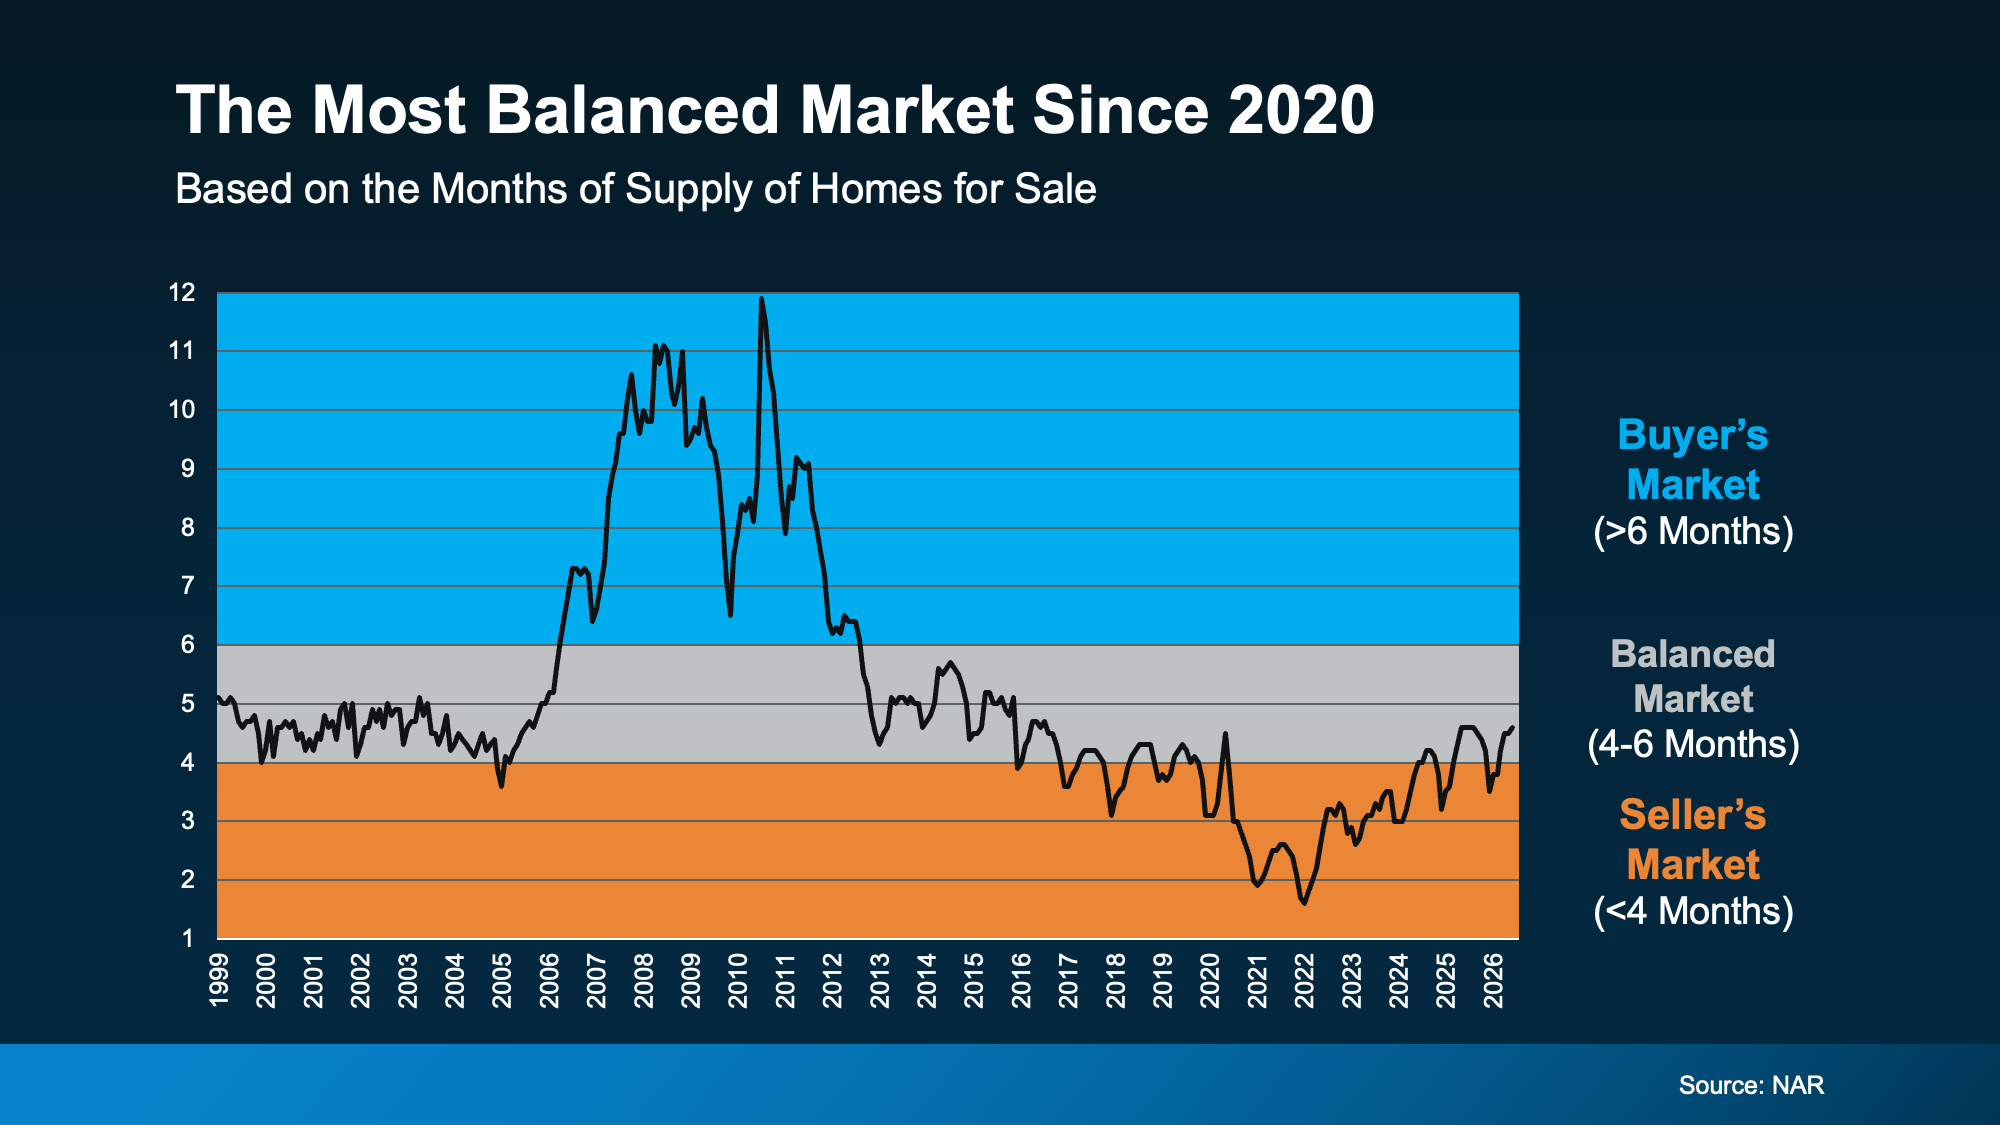
So how do you know which market you’re in? There’s one number that tells the story faster than anything else: the months’ supply of homes for sale. It’s the clearest signal of who’s got leverage – and what strategy you’ll need. Think of it like this.

Imagine no additional homes were listed starting today. Months’ supply tells us how long it would take to sell everything that’s currently on the market based on today’s demand.

Generally speaking, if months’ supply is:

  • Fewer than 4 months: Sellers usually have the advantage.
  • 4 to 6 months: Buyers and sellers are on more equal footing.
  • More than 6 months: Buyers can usually negotiate for a better deal.

Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):

a graph of a market

That means, as a whole, the market has finally moved back into a much more balanced range after years of being tilted in sellers’ favor. While that may look like the scales have tipped only slightly, it’s enough to make a real difference in what strategy you’ll need for your move – at least in most places.

The Tale of Two Markets: Why ‘Balanced’ Doesn’t Mean the Same Thing Everywhere

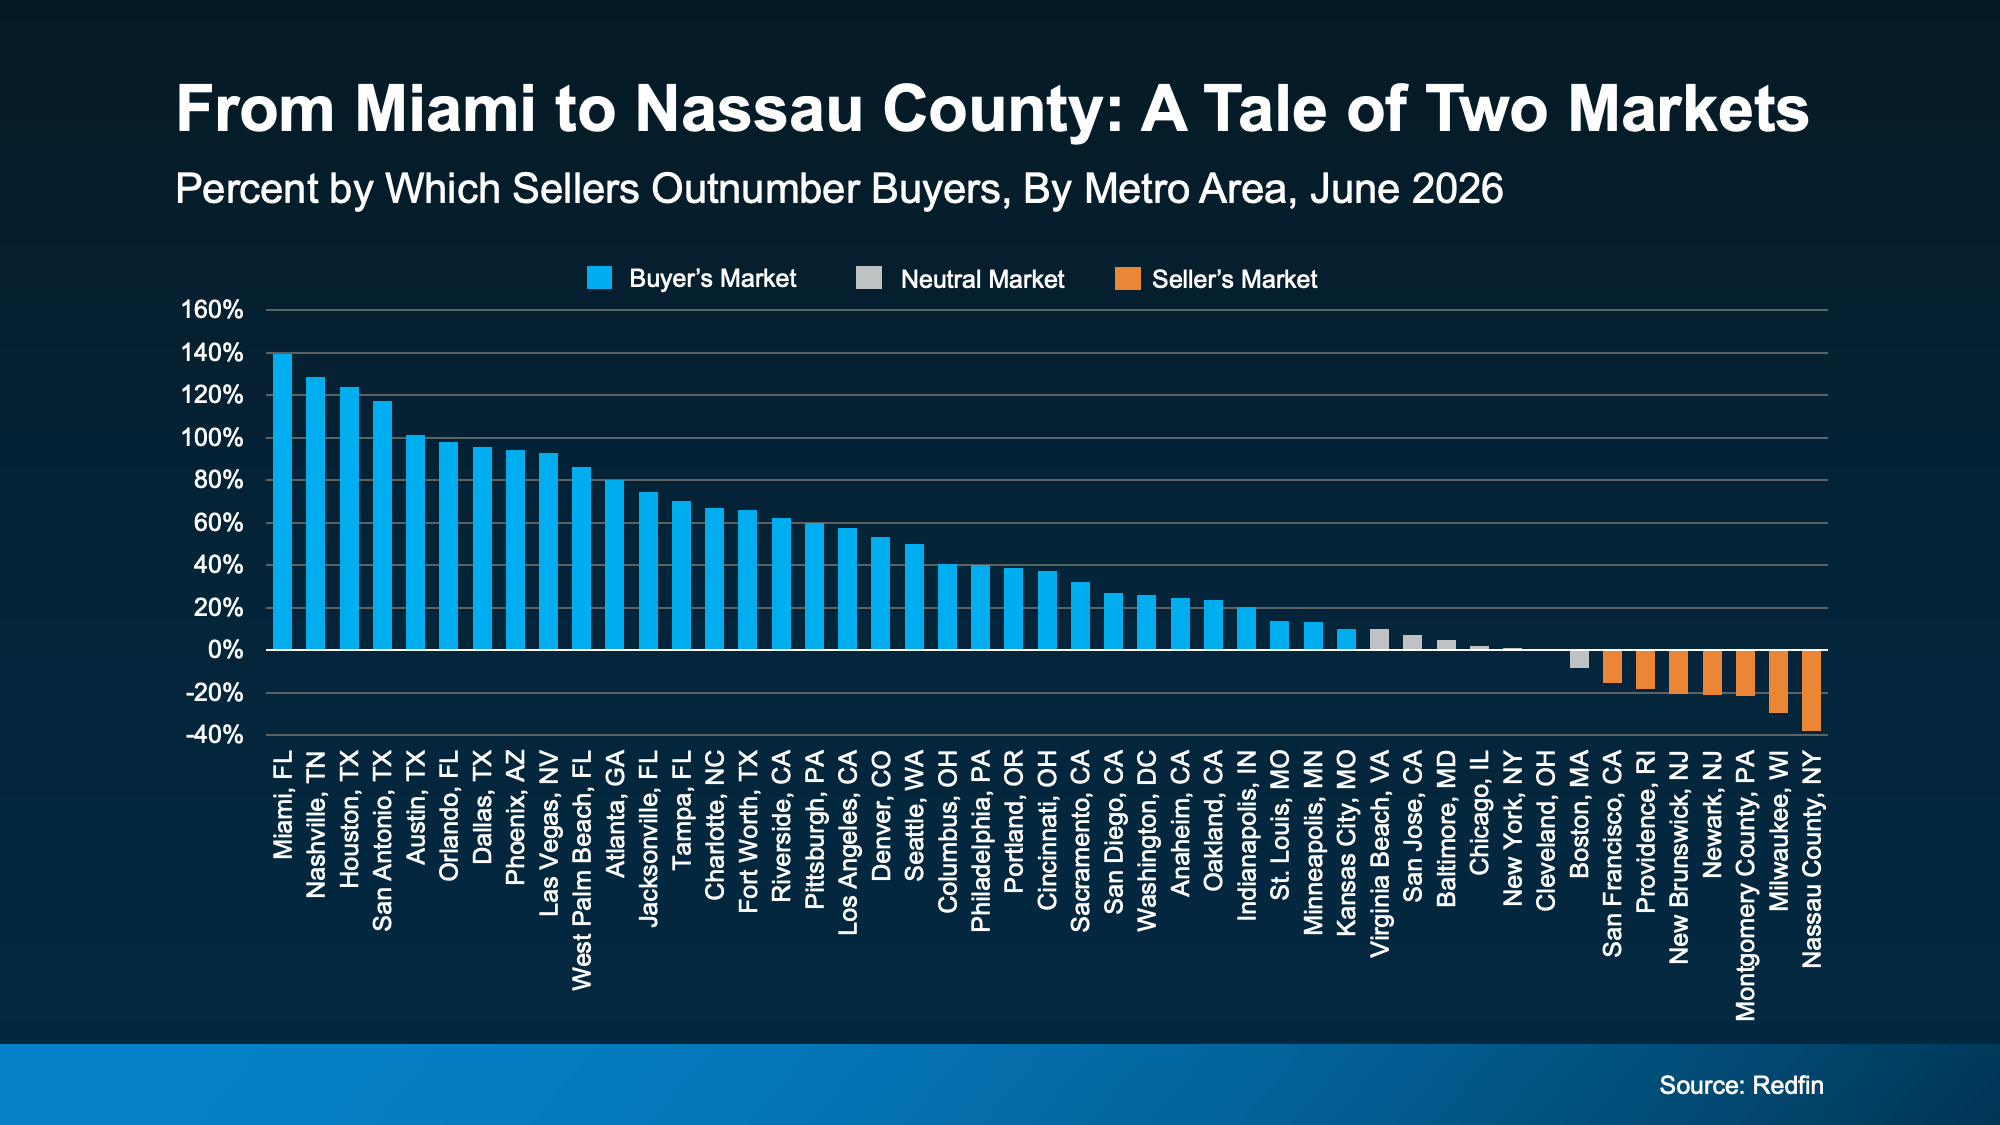
Redfin data helps shed some light on how this shakes out across the country. It breaks down which cities are leaning in either direction (see graph below).

  • Some markets give buyers more leverage. Those are in blue.
  • Some still favor sellers. That’s the orange.
  • Others fall somewhere in between. Those are gray.

a graph of a marketNotice anything? A lot more places are seeing more buyer-friendly conditions right now.  In fact, this is the most buyer-friendly market we’ve seen in nearly 6 years.
But don’t take that as buyers have the upper hand everywhere.

There are still cities where sellers still have the power. And if you’re in one of them, your approach to selling or buying looks completely different than it would in a buyer-leaning market.

The Biggest Mistake You Can Make Right Now

That’s why the biggest mistake isn’t thinking it’s finally a buyer’s market. And it isn’t thinking it’s still a seller’s market either. It’s making any assumption without talking to an expert agent first.

Today’s market is incredibly local. In one market, a buyer may be getting thousands of dollars in concessions from a seller. And a homeowner may have to consider dropping their price.

But in another, a buyer may be stressed about coming in with their best offer, or they may lose out on the home to another buyer. And a seller may still be seeing strong demand and prices inching higher.

Same overall housing market.

Very different experiences.

The truth is what’s happening in your back yard affects everything from pricing your house to making an offer to negotiating repairs or concessions. And that’s why an agent’s local knowledge matters more now than ever before.

Your plan has to be based on your neighborhood – and only an agent has the expertise to get that right.

Bottom Line

This market isn’t one-size-fits-all.

If you’re wondering who has the upper hand where we live, let’s talk. I’ll show you exactly what the numbers look like in our market – and what strategy gives you the best shot at getting what you want.

Buyers • Mortgage Updates • Sellers • August 19, 2026

Here’s Why Mortgage Rates Are What They Are Right Now

If you’re waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there’s a number working behind the scenes that’s actually good for you right now. It’s called the spread, and once you understand it, you may see today’s rates in a whole new light.

The Pattern That’s Held for 50+ Years

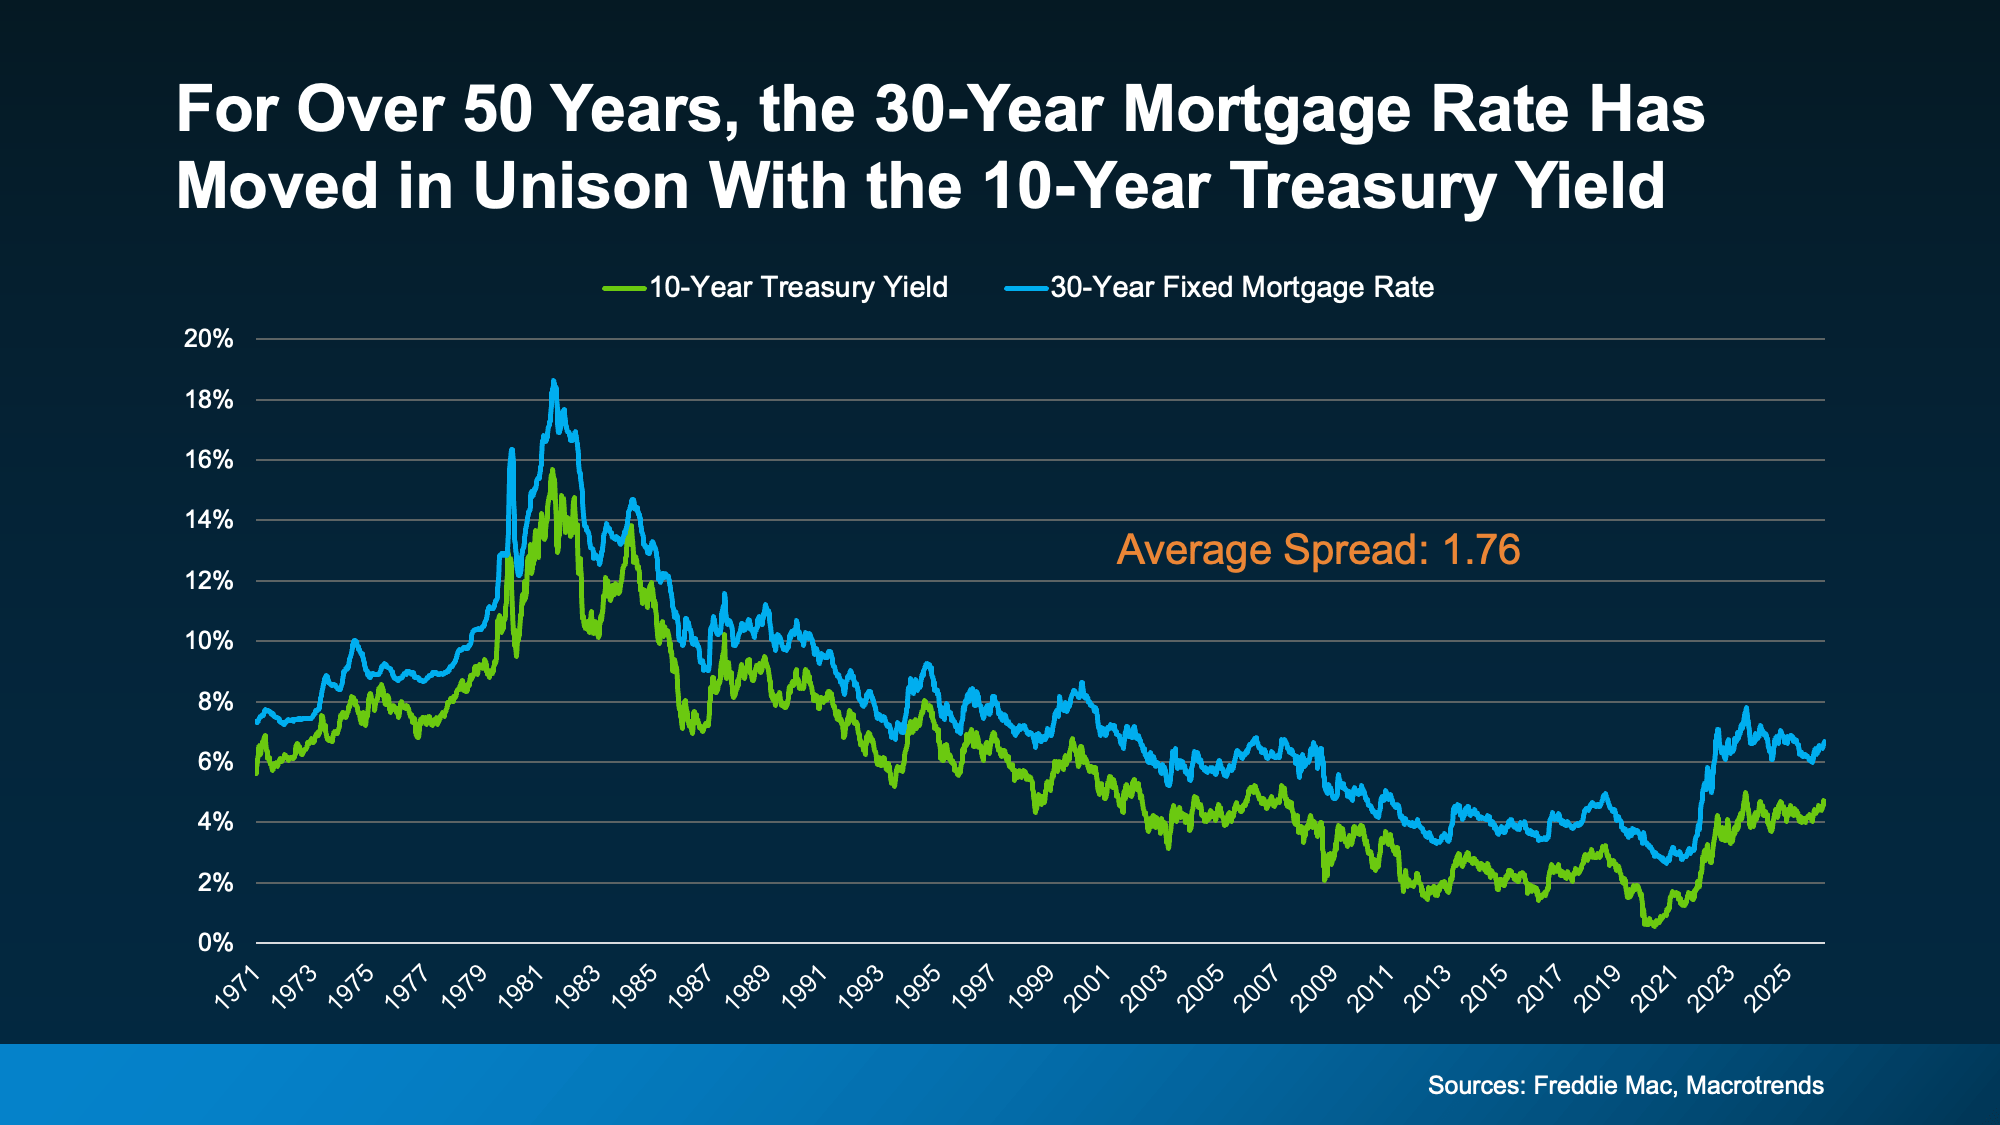
For starters, mortgage rates don’t move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.

It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):

a graph of a graph showing the number of mortgage rates

The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.

One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon

If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.

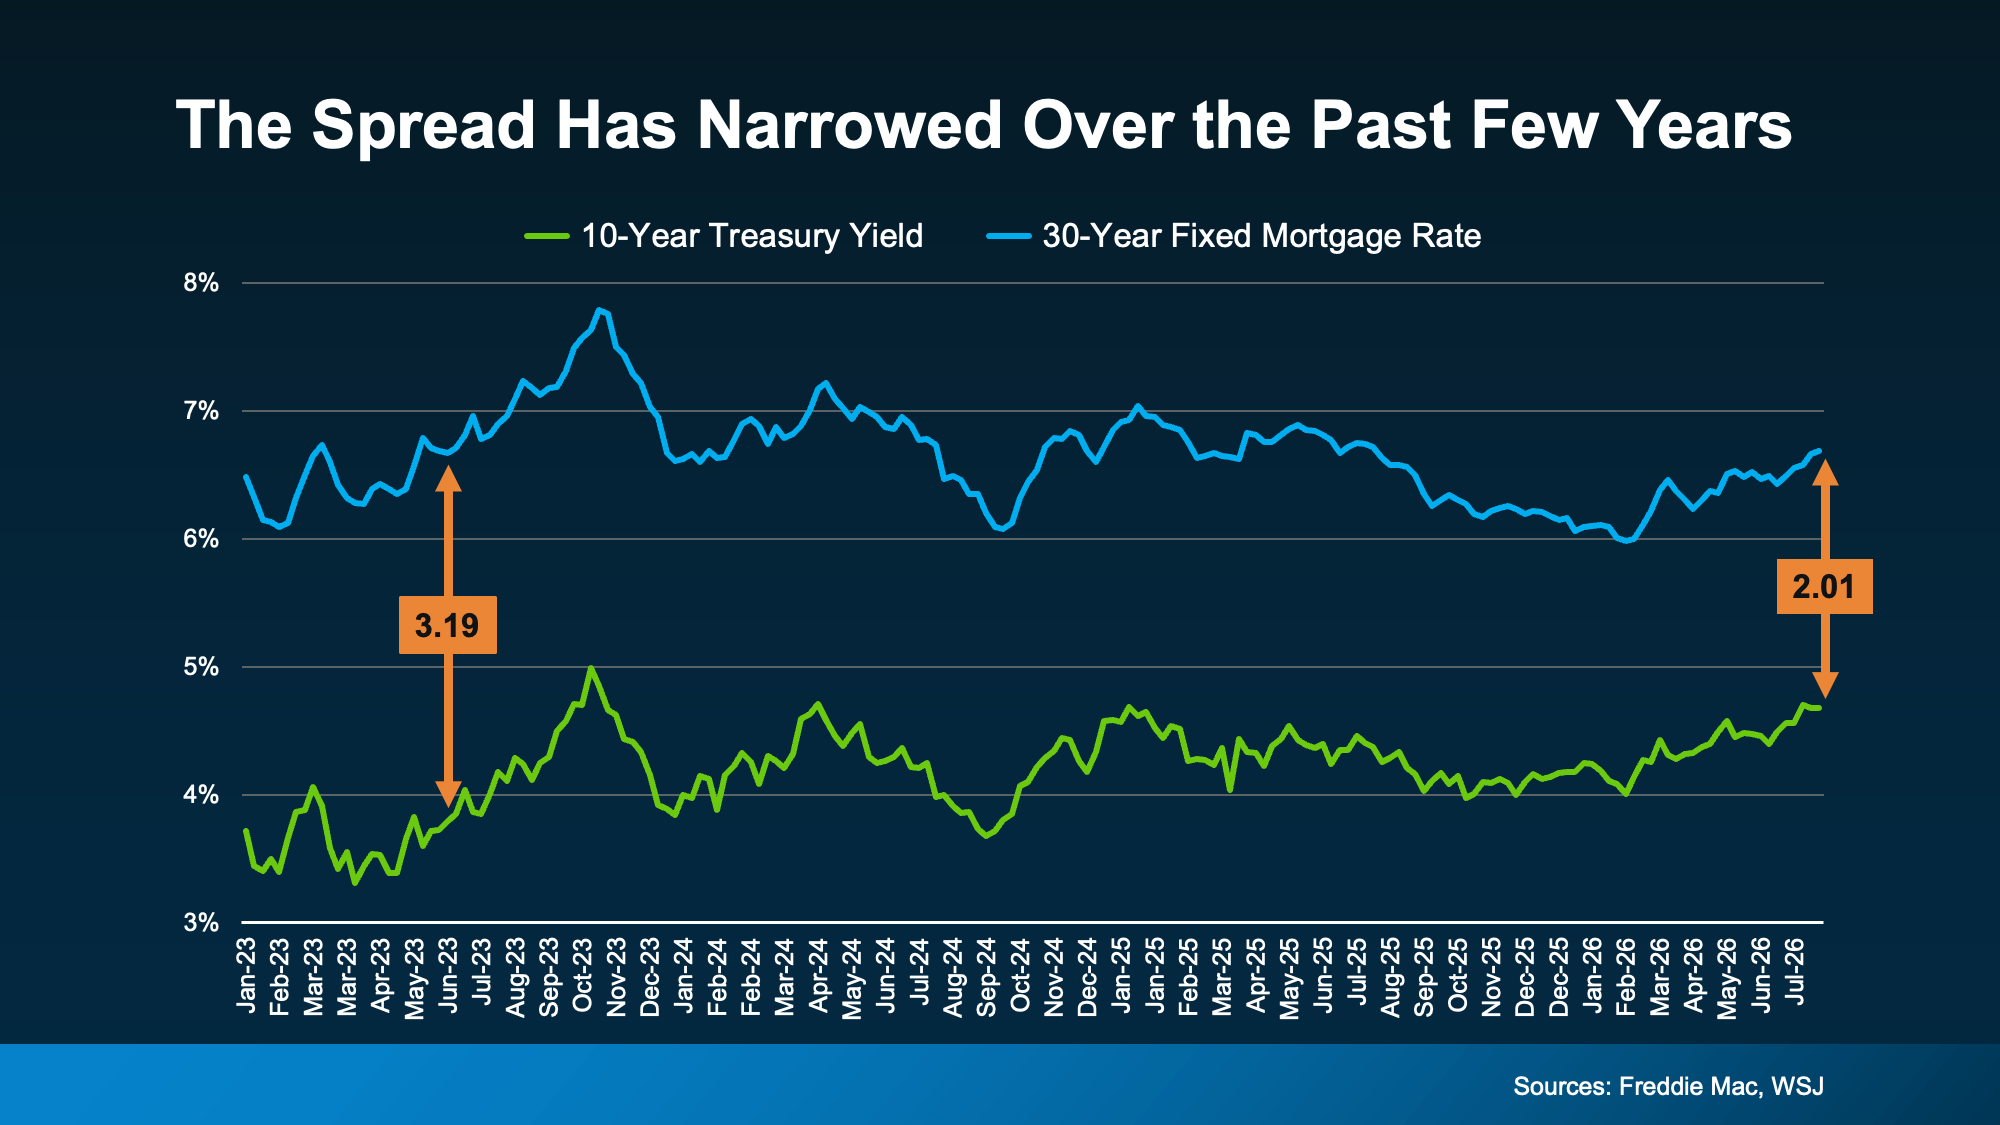
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.

Now here’s the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):

a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.

Why Mortgage Rates Aren’t Higher Right Now

Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today’s 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):

a graph of a graph showing a rate of interest

If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.

But now, thanks to the spread narrowing recently, today’s rate sits around 6.69%. That’s the middle scenario in that visual. That’s a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:

“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”

Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That’s only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.

In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.

Bottom Line

That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they’re better than they could’ve been. If you want help figuring out what that means for your monthly payment, reach out to a local lender

Agent Value • Buyers • Sellers • August 12, 2026

Seriously? 5 Reasons You Probably Shouldn’t Hire Me…

If you’re looking for a Realtor who will simply show you houses, tell you everything looks great, and do whatever it takes to get a deal closed, I’m probably not your guy.

And I’m completely comfortable saying that.

Real estate is a big decision. Often one of the biggest financial decisions you’ll make. So I don’t believe my job is to tell you what you want to hear or push you toward a transaction.

My job is to help you make the right decision for you.

That means sometimes asking harder questions, pointing out things you may not have considered, and even telling you when I think you should walk away.

Here are five reasons you probably shouldn’t hire me.

1. Don’t hire me if you want to start with houses.

I want to start with you.

Before we start scrolling through listings or scheduling showings, I want to understand what you’re actually trying to accomplish.

What matters most to you?

What are your priorities?

What are you willing to compromise on—and what are you not?

Because finding a house is relatively easy.

Finding the right house for your life, your goals, and your financial situation takes a lot more thought.

The house is the vehicle. You are the destination.

2. Don’t hire me if you only want to hear what you want to hear.

You’re not hiring me for agreement.

You’re hiring me for judgment, experience, and perspective.

Sometimes that means I’ll tell you something you don’t want to hear.

Maybe the house you’re excited about has issues that aren’t obvious at first glance.

Maybe the price doesn’t make sense.

Maybe the neighborhood doesn’t fit what you’re really looking for.

Or maybe it’s simply not the right time for you to buy.

My job isn’t to be the person who says, “Absolutely! Let’s do it!” every time.

My job is to help you see the decision clearly—even when the conversation isn’t necessarily the one you hoped we’d have.

3. Don’t hire me if you want to overpay.

When representing buyers, my clients have averaged 97.5% of the listing price.

That number matters because I don’t believe winning a house means paying whatever it takes to get it.

Buying the house isn’t the goal. Buying it well is.

There will always be another house.

There will always be another opportunity.

My job is to help you understand the market, evaluate the property, understand its value, and negotiate from a position of knowledge—not emotion.

Because getting the keys feels great.

Getting the keys without wondering if you paid too much feels even better.

4. Don’t hire me if getting the deal closed matters more than making the right decision.

This might be the most important one.

Sometimes the best advice I can give a client is:

“Don’t buy this house.”

That isn’t always the easiest thing for a Realtor to say.

But a commission is never a good enough reason for you to make a bad real estate decision.

There are plenty of reasons a transaction might look good on paper but not make sense for the person buying it.

Maybe the inspection uncovered something significant.

Maybe the numbers don’t work.

Maybe the property doesn’t fit your long-term plans.

Or maybe your gut is telling you something your excitement is trying to ignore.

I’d rather help you walk away from the wrong house than help you close on a decision you’ll regret.

5. Don’t hire me if you just want someone to open doors.

That’s the easy part.

Yes, I’ll open doors.

But my job doesn’t end there.

I’m bringing perspective, preparation, construction knowledge, negotiation experience, market knowledge, and a clear plan to the process.

I’m looking at the things you may not notice.

I’m asking questions you may not think to ask.

I’m helping you understand what you’re actually buying—not just how it looks in the listing photos.

Because there’s a big difference between facilitating a transaction and advising someone through one.

So, who should hire me?

Someone who wants more than a Realtor.

Someone who wants an advisor.

Someone who values honest feedback over easy answers.

Someone who wants to understand the risks, opportunities, numbers, and long-term implications before making a decision.

Someone who understands that the goal isn’t simply to buy or sell a house.

The goal is to make a decision that makes sense for you.

A good Realtor can help you complete a transaction.

A great advisor remembers the transaction isn’t the point. You are.

Helping People Succeed.

Buyers • Sellers • August 10, 2026

Home Price Growth Slowed Down. That May Be Changing.

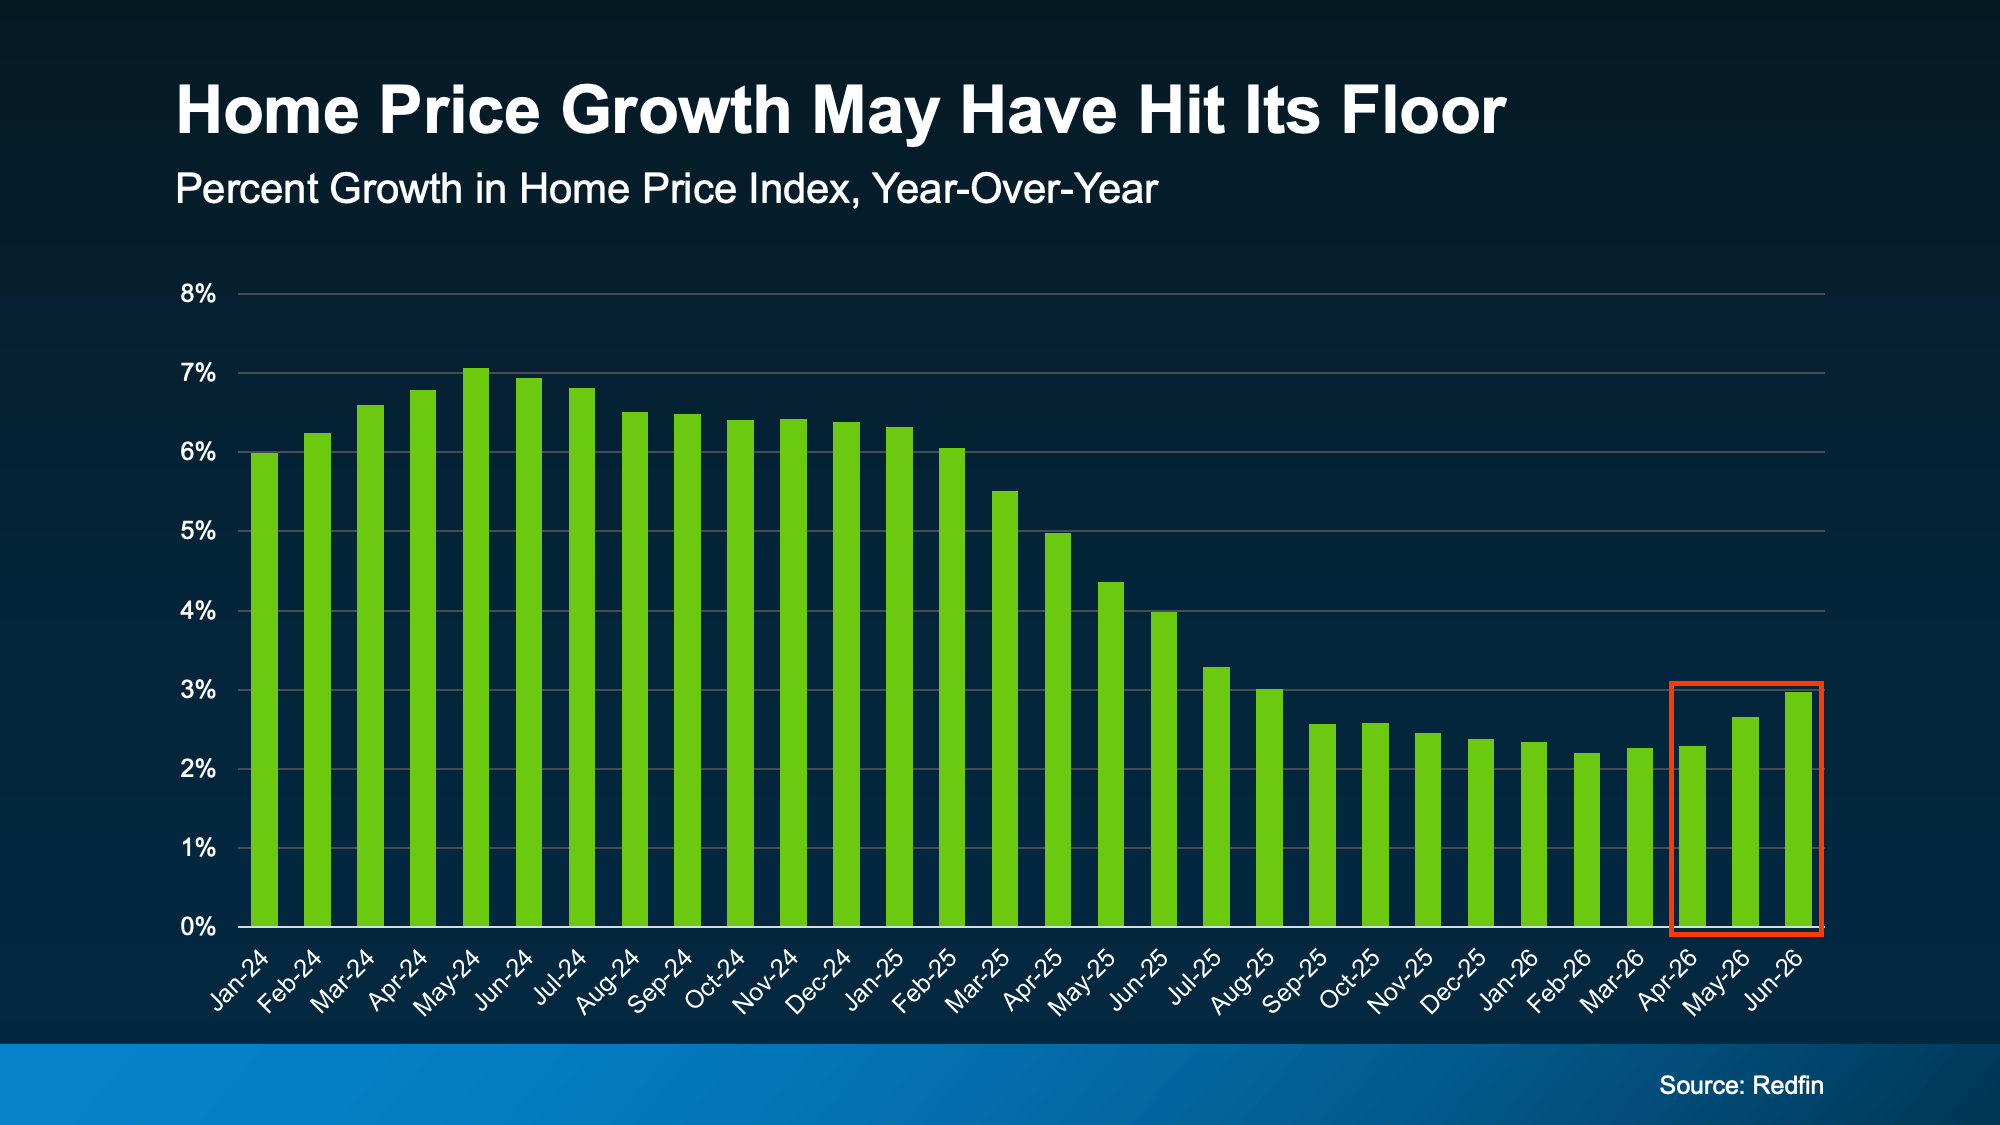
After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you.

The Numbers May Be Starting To Turn

For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn.

a graph of growth in a number of years

While a couple months of data doesn’t necessarily mean this will be a lasting trend, there are some other signs that this could continue.

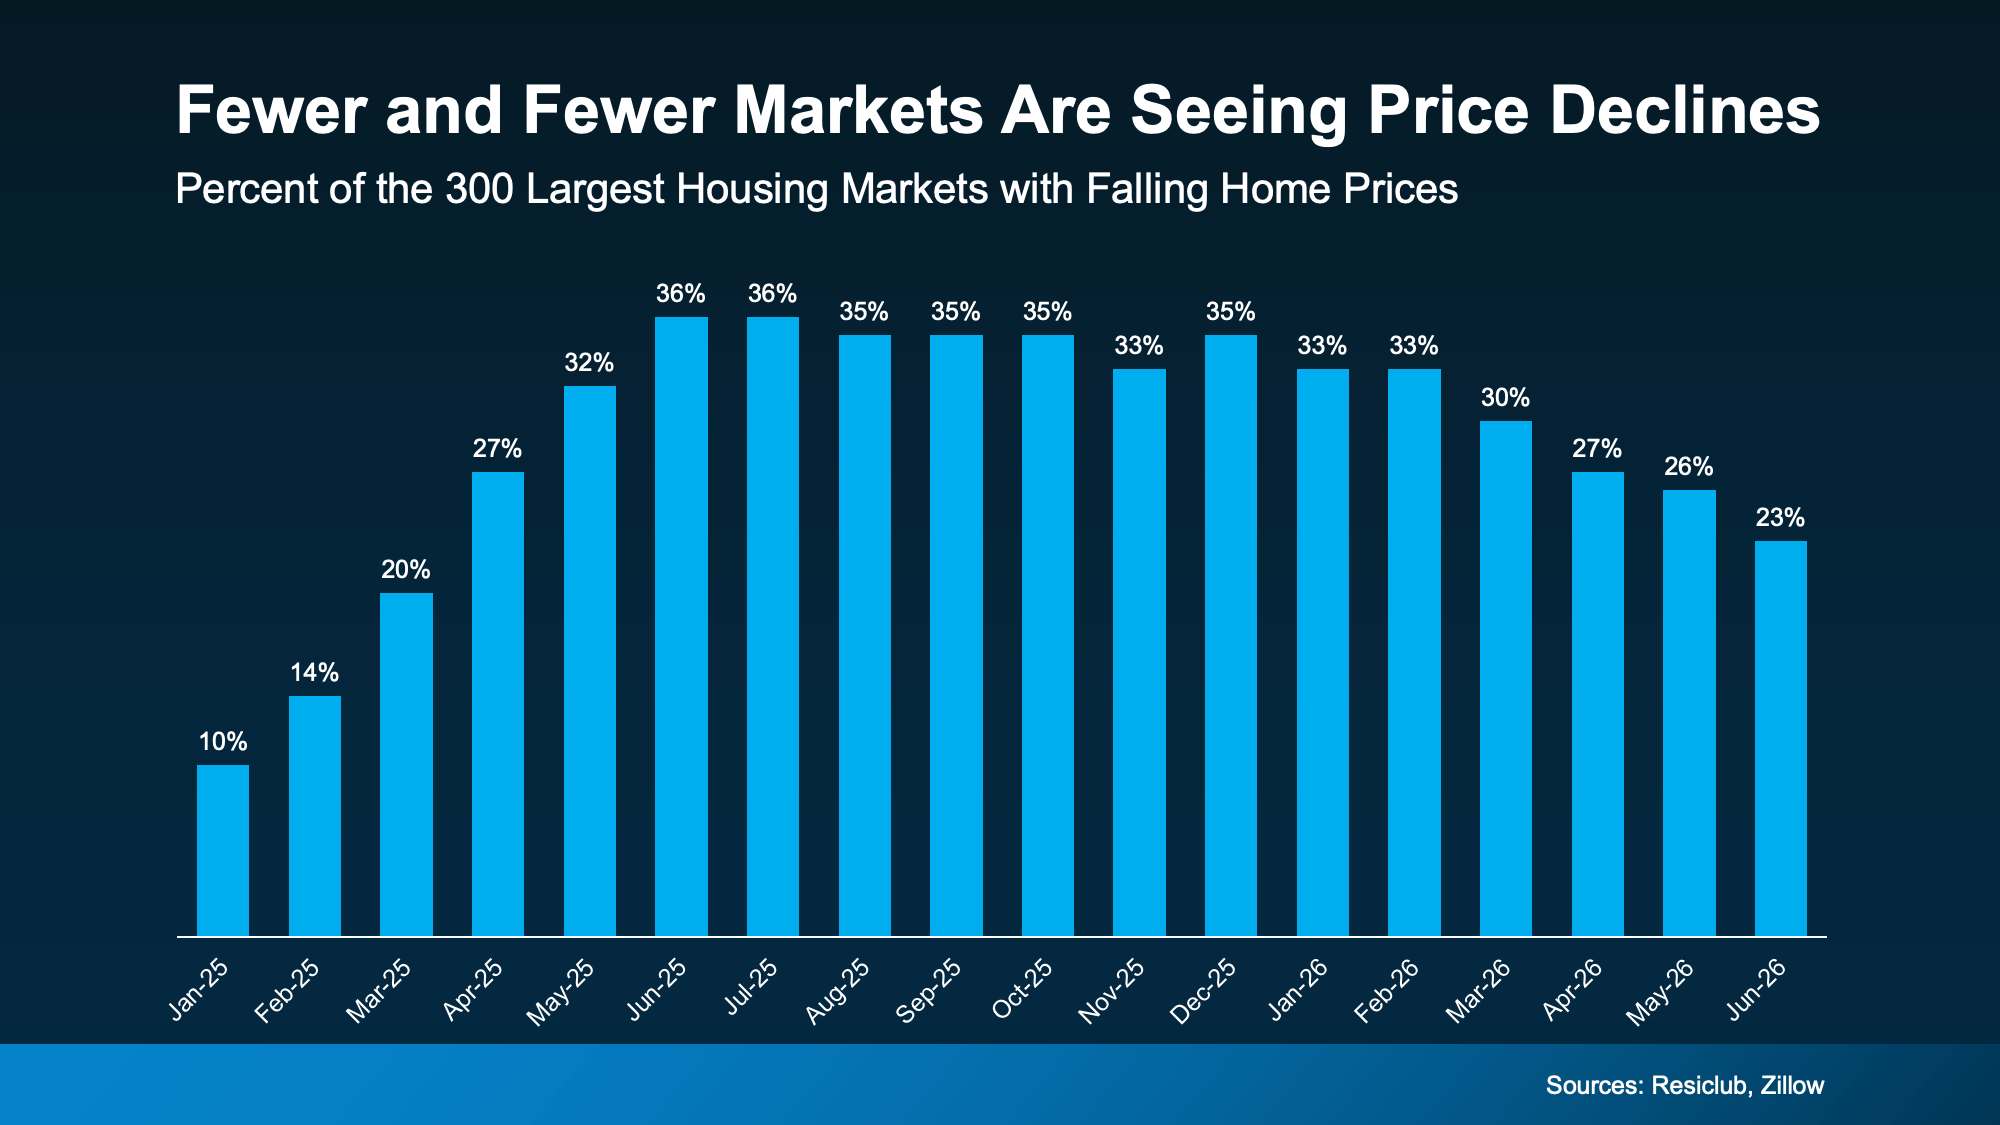
For example, fewer markets are seeing prices decline. According to ResiClub and Zillow, about 36% of the 300 largest housing markets had falling prices as of the middle of last year. Since the start of this year, that share has been shrinking. Now? Only 23% are experiencing those mild dips (see graph below):

a graph of the price of a house

When fewer markets see prices falling, that means more markets are seeing prices rise again.

And forecasts suggest this shift has room to run. On average, experts project home prices will rise about 2.3% nationally this year. And for that to happen, price growth would have to pick up a bit in the second half of 2026.

But Remember, Real Estate Is Local

While it looks like national prices may be starting to pick back up a tiny bit, that doesn’t mean that’s what’s happening in your neighborhood.

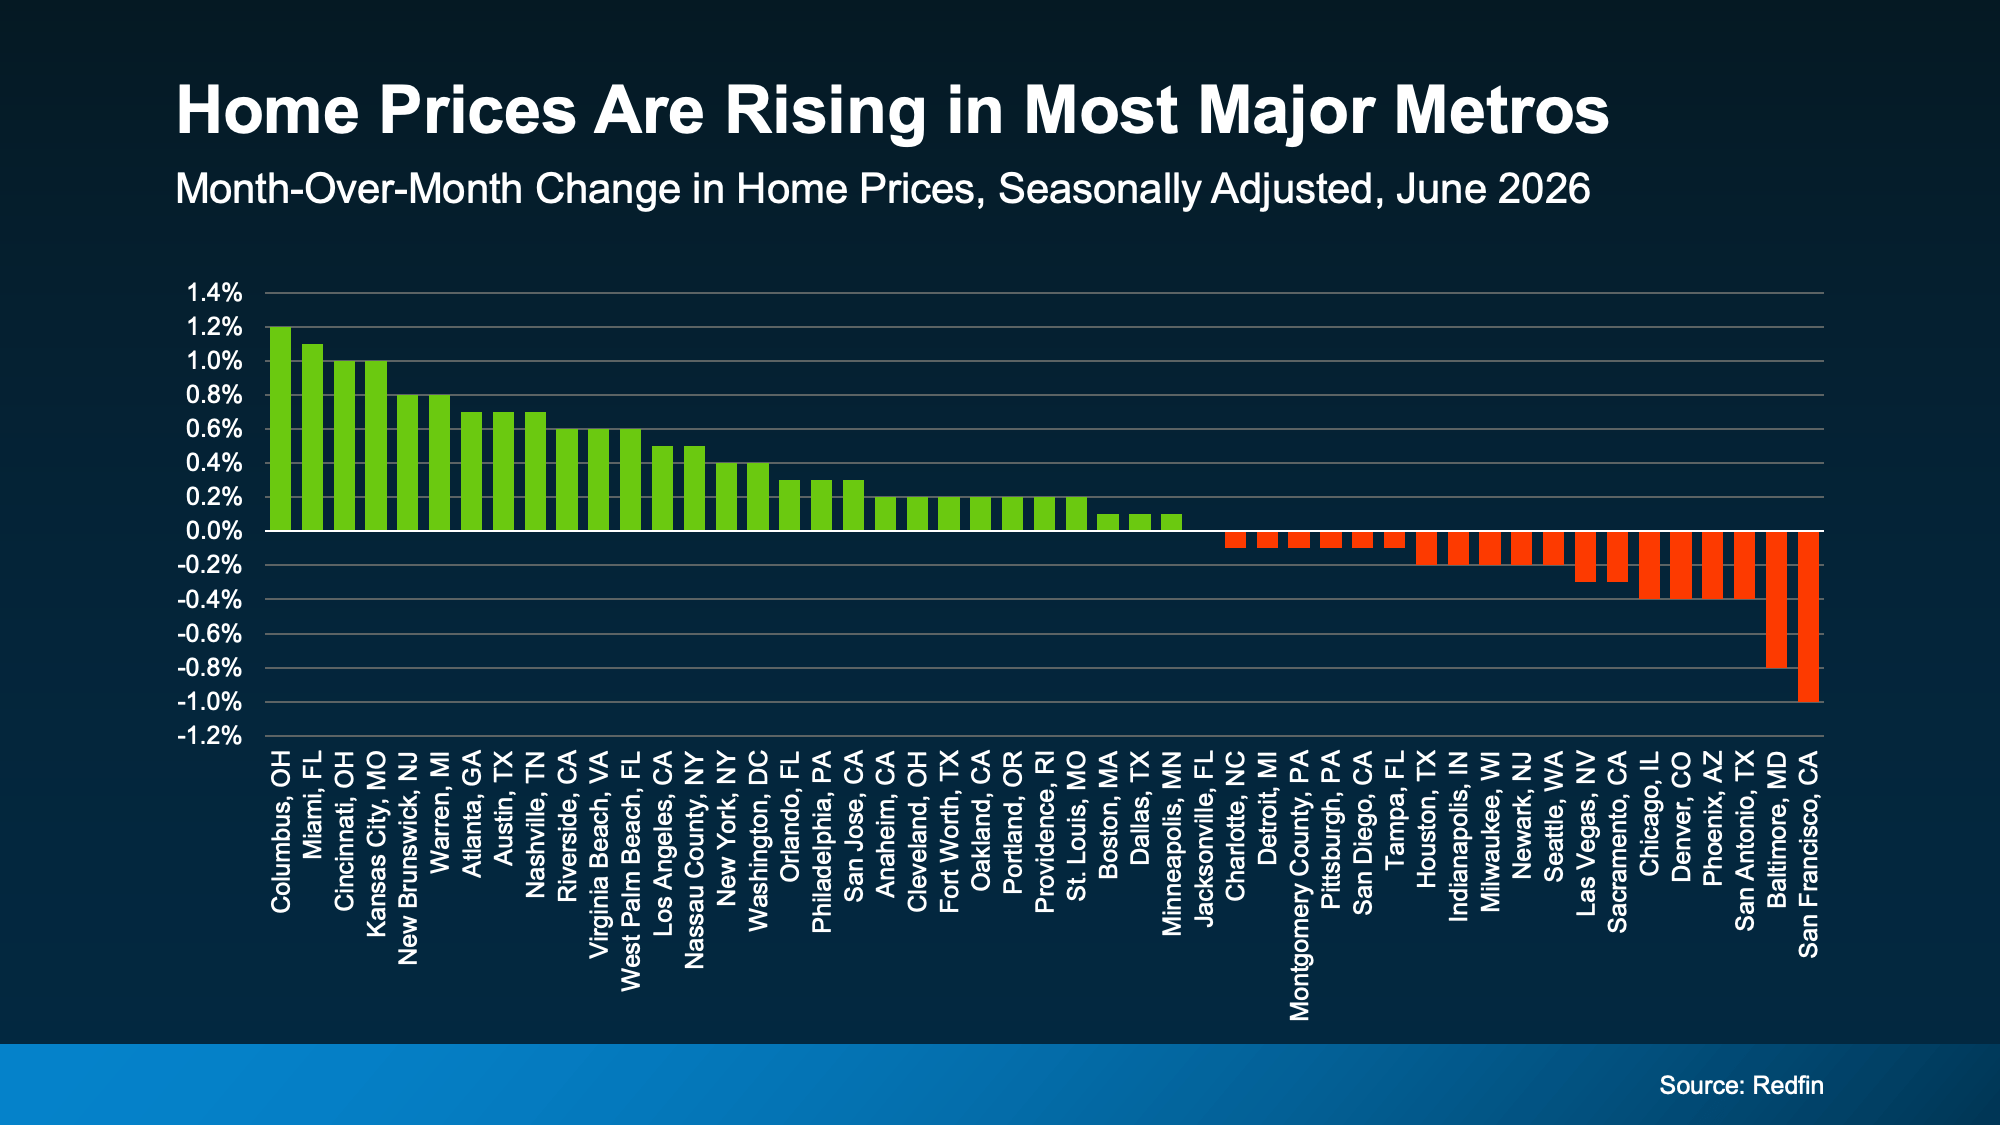
National home prices are really just an average of hundreds of local markets. Some are climbing faster. Others are still cooling. But one reason the national average may be looking up is because a growing number of metros may actually be net positive for prices this year.

Not long ago, the major metros were split about 50/50 – half seeing prices rise and half seeing them fall. Now, that balance looks like it’s starting to tip in a more positive direction. Just last month, more than half of the major metros saw prices go up, according to Redfin (see graph below):

a graph of prices on a dark background

As Selma Hepp, Chief Economist at Cotality, explains:

“. . . local markets continue to tell very different stories. Annual home price growth has changed little since the start of the year, but some markets, especially those supported by strong job and income growth in the West and more affordable Midwest markets, have seen notable acceleration in price gains.”

What This Means for You

Home price headlines can be confusing because they don’t always tell the full picture. Lean on an agent to understand what’s happening in your local market and what the early signs say for where prices may go from here.

That’s the best way to stay one step ahead of the market.

If you’re buying: slower price growth has worked in your favor. You’ve had more room to negotiate and a budget you could plan around. If price growth is picking up in your area, buying now may mean paying less than you would later this year.

If you own a home: you’ve been gaining equity all along, even while growth moderated. If growth keeps picking up, those gains could speed up, too. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), projects the typical homeowner will gain roughly $16,000 in housing wealth this year. And if you’re thinking about selling, this shift is a good early sign for you. Just remember, the market is still pretty balanced and buyer-friendly in a lot of areas right now.

Home price growth slowed way down, and now it’s showing early signs of picking back up. Whether you’re buying or selling, let’s connect so you can see exactly what prices are doing in our local market and what that means for your plans.

Bottom Line

Home price growth slowed way down, and now it’s showing early signs of picking back up. Whether you’re buying or selling, let’s connect so you can see exactly what prices are doing in our local market and what that means for your plans.

Housing Market Updates • Sellers • August 4, 2026

Selling a Luxury House? Here’s Why Now Is a Good Time

If you own a luxury house, you’re in a stronger spot than most sellers right now. While much of the market has cooled, the high-end tier hasn’t. Sale prices and buyer demand are both up. So if you’re considering selling, now could be a great time to make your move.

Luxury Is Leading on Price

Let’s start with prices. But before we get into it – what actually counts as a luxury home? Generally, these are homes in the top 5% price range for the area, so it varies depending on where you live.

But what’s interesting is that according to the latest data from Redfin, sale prices for luxury houses have risen about three times faster than for non-luxury.

Right now, the typical home’s sale price is up about 1.5% year-over-year. But high-end homes? Their sale prices have gone up nearly 5% since last year (see graph below):

a graph of sales

That’s a bigger deal than it sounds like.

Despite all the talk about slowing price growth lately, sale prices in this segment of the market may be rising faster than you’d expect based on the headlines. That’s going to be a good thing if you’re thinking about selling. And rising sale prices are only half the story.

Buyers Are Showing Up, Too

While so many headlines are talking about how buyers are pulling back, that’s not necessarily true when it comes to luxury homes. In fact, right now, it looks like the higher the price point, the more active the buyers.

Lawrence Yun, Chief Economist with the National Association of Realtors (NAR), explains:

“The luxury market has really performed better compared to the lower price point. . . . if we look at price points, any home priced under $250,000, virtually no change in unit sales from one year ago. Then you go into the upper price category, and home sales are up about 10% from one year ago. But the million dollar-plus homes, it is up by 18% from one year ago.“

Basically, more homes are selling on the upper end of the market. A big reason is that high-end buyers tend to feel less of the affordability pressure weighing on many households today, so they keep buying even when the wider market slows.

That demand also means that luxury houses don’t stay on the market as long as they used to.

Luxury Houses Are Selling Relatively Quickly

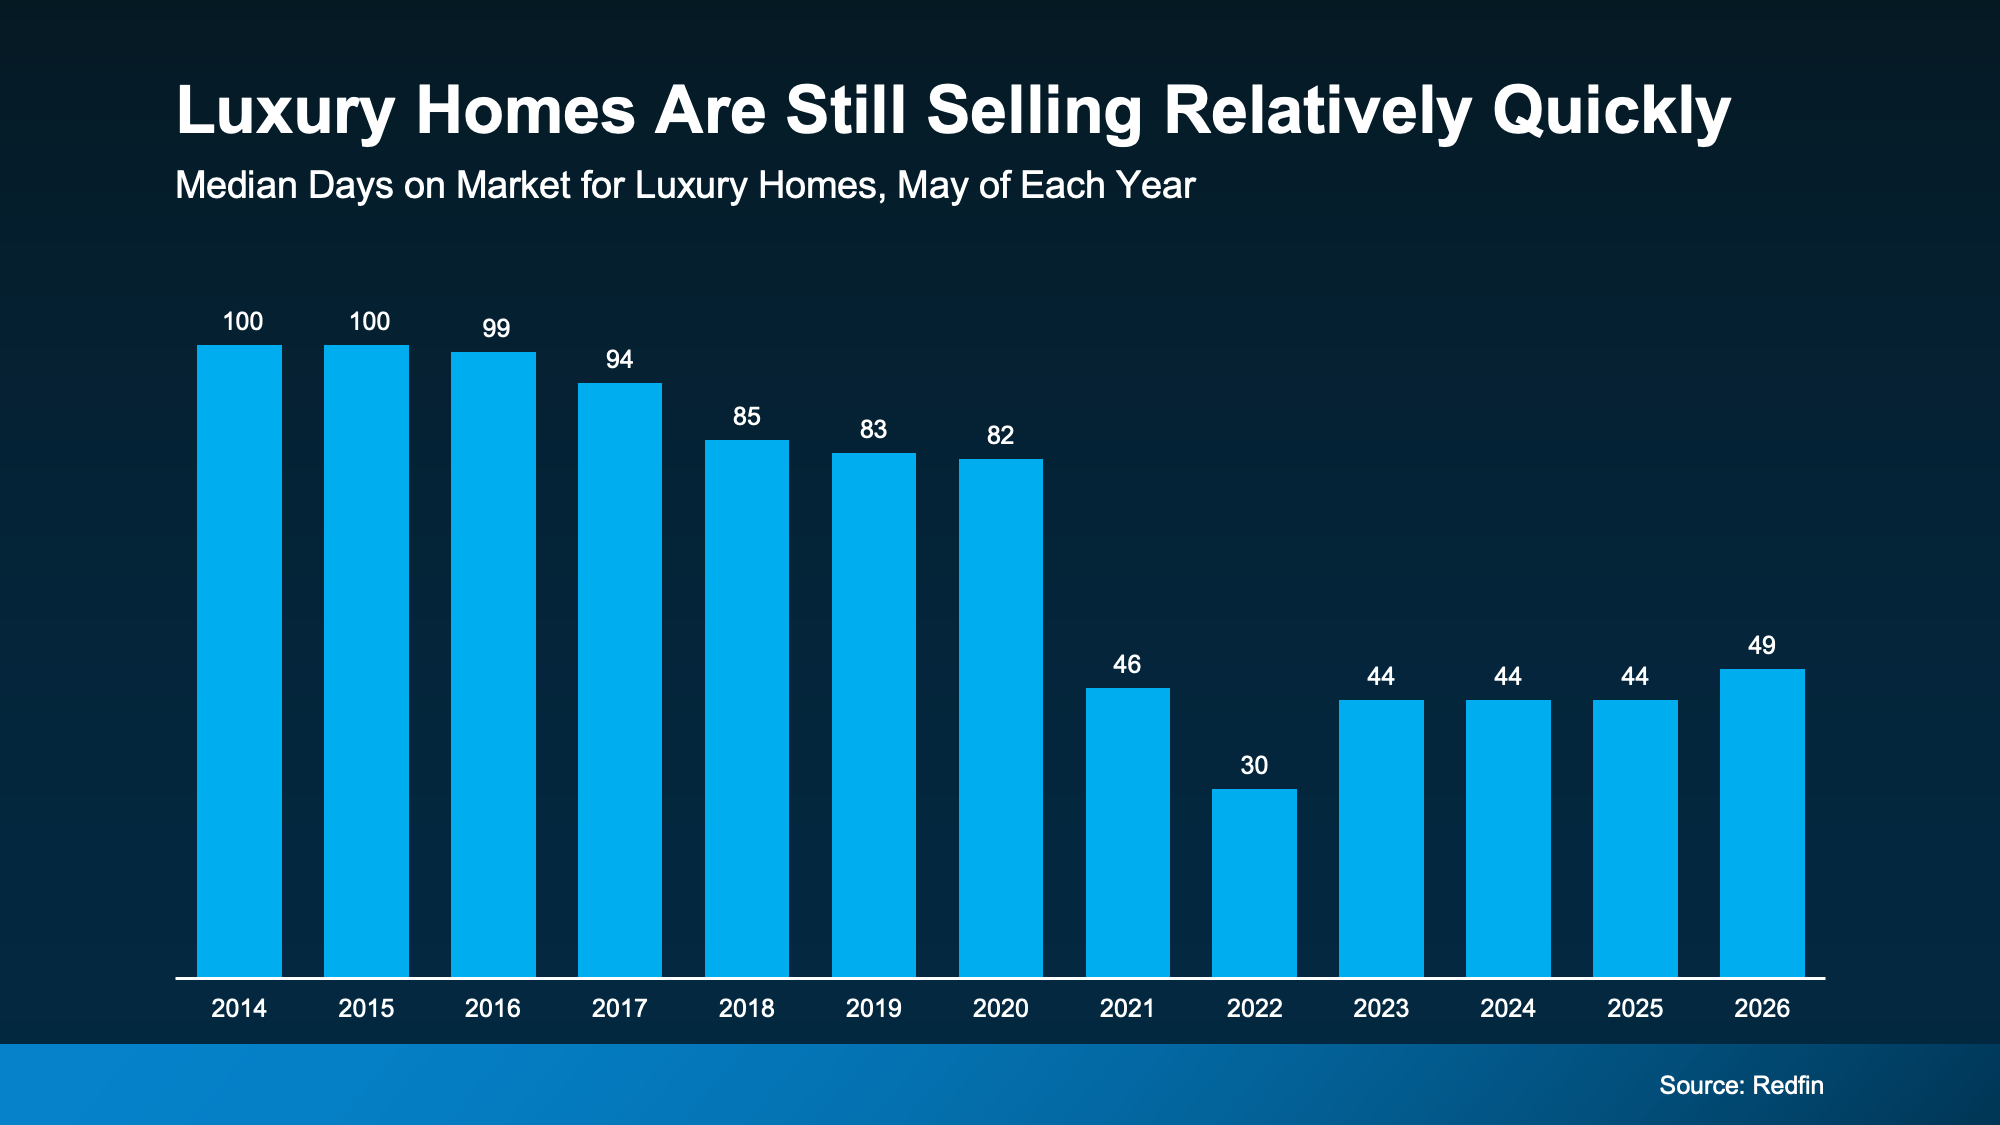
According to the most recent data from Redfin, for luxury homes the median number of days on market is under 50. That’s much faster than pre-pandemic norms going even as far back as 2014 (see graph below):

a graph of sales in a market

That means you probably won’t spend a ton of time sitting in limbo wondering when you’ll get an offer.

Bottom Line

Selling a high-end house is a big decision, and you deserve to feel confident going in. With sale prices climbing and buyers active at the top, this is a strong window to make your move.

Ready to cash in? Let’s talk strategy.

Buyers • Sellers • July 29, 2026

Why Americans Still Believe Real Estate Is the Best Long-Term Investment

For the 14th Year in a Row

For the 14th year in a row, Americans have named real estate as the best long-term investment.

That’s an impressive streak—especially considering everything the housing market has experienced over the past decade. From rising mortgage rates and inflation to shifting market conditions, real estate has consistently remained the investment Americans trust the most.

The Numbers Speak for Themselves

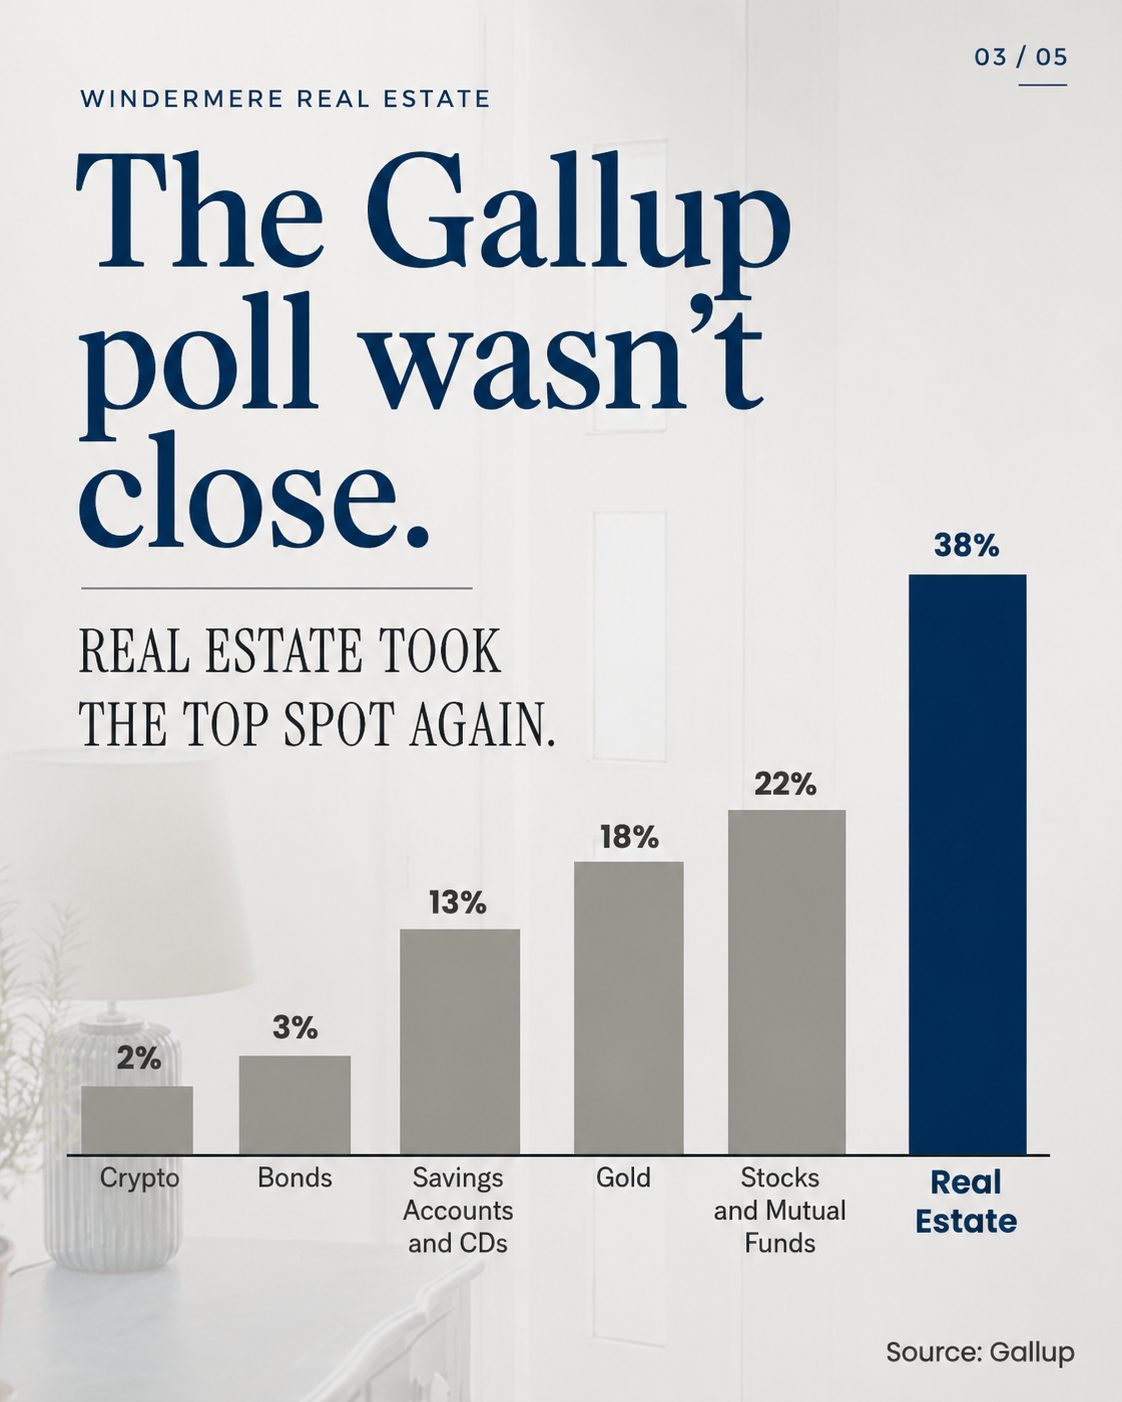
The Gallup poll wasn’t even close.

Real estate earned the highest percentage of votes as the best long-term investment, finishing well ahead of stocks, gold, savings accounts, bonds, and cryptocurrency.

Why Real Estate Continues to Lead

Unlike stocks, bonds, or savings accounts, a home provides value beyond dollars and cents.

Yes, it has the potential to appreciate over time and help build long-term wealth through equity. But it also provides something just as important—a place to create memories, build stability, and put down roots.

For many homeowners, their home becomes both their largest financial asset and the center of their everyday lives.

Buying Smart Matters

Of course, not every home purchase automatically becomes a great investment.

The key is buying the right home for your goals and financial situation. Factors like:

  • Location
  • Purchase price
  • Property condition
  • Monthly affordability
  • Long-term plans

all play an important role in making a sound real estate decision.

That’s why working with an experienced real estate professional can make such a difference. Having someone who understands the market, negotiates on your behalf, and helps you evaluate opportunities can help you make a confident, informed decision.


Thinking About Buying?

Many buyers wonder if they should wait for the “perfect” market. The reality is that there is rarely a perfect time to buy. The best time is when your finances, lifestyle, and long-term goals align.

Every buyer’s situation is different, which is why personalized guidance is so valuable.

Buyers • Sellers • July 27, 2026

The “Take It or Leave It” Attitude Is Fading from the Market – What That Means for You

Negotiations are back. More buyers are asking for better deals, and more sellers are giving them. Builders are throwing in extras, too.

That’s why whether you’re buying or selling today, there are two terms you’ll hear a lot: concession and incentive.

  • A concession is something a seller agrees to during negotiations to get a deal done.
  • An incentive is a perk a builder (or a seller) advertises upfront to attract buyers.

Let’s run through what you need to know about both and how they could play a role in your move.

More Sellers Are Agreeing to Concessions

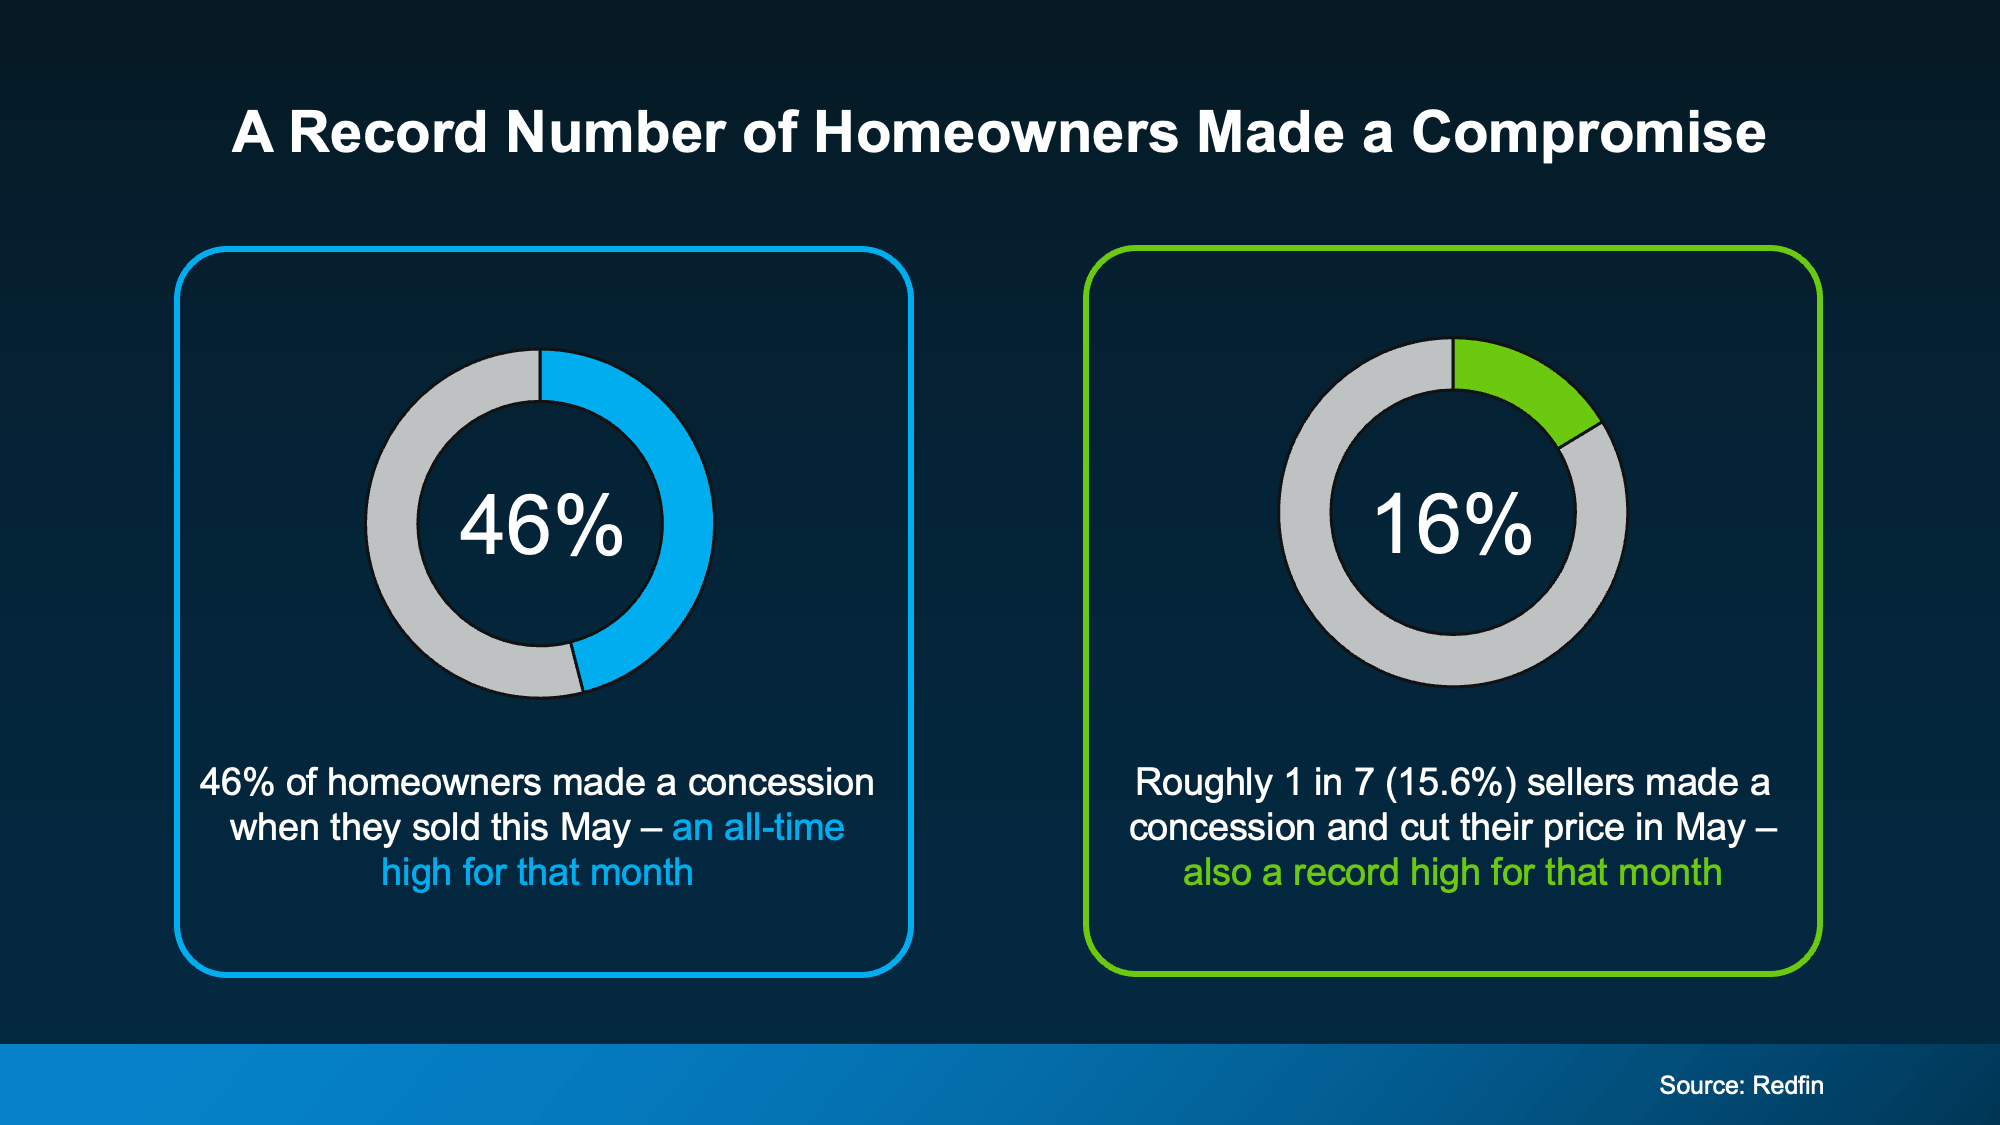
Almost half (46%) of homeowners who sold recently gave the buyer a concession, according to Redfin. That’s the highest share on record for this time of year. And roughly 1 in 7 (16%) sellers went a step further, cutting their asking price and offering a concession on top (see chart below):

a diagram of a homeowner's market

So, what kind of concessions are we talking about?

A seller might cover part of your closing costs, take care of a repair, or offer a credit that trims your upfront costs. It’s how they keep a deal on track when buyers have more options to choose from – and homeowners aren’t the only ones compromising.

Builders Are Cutting Prices, Too

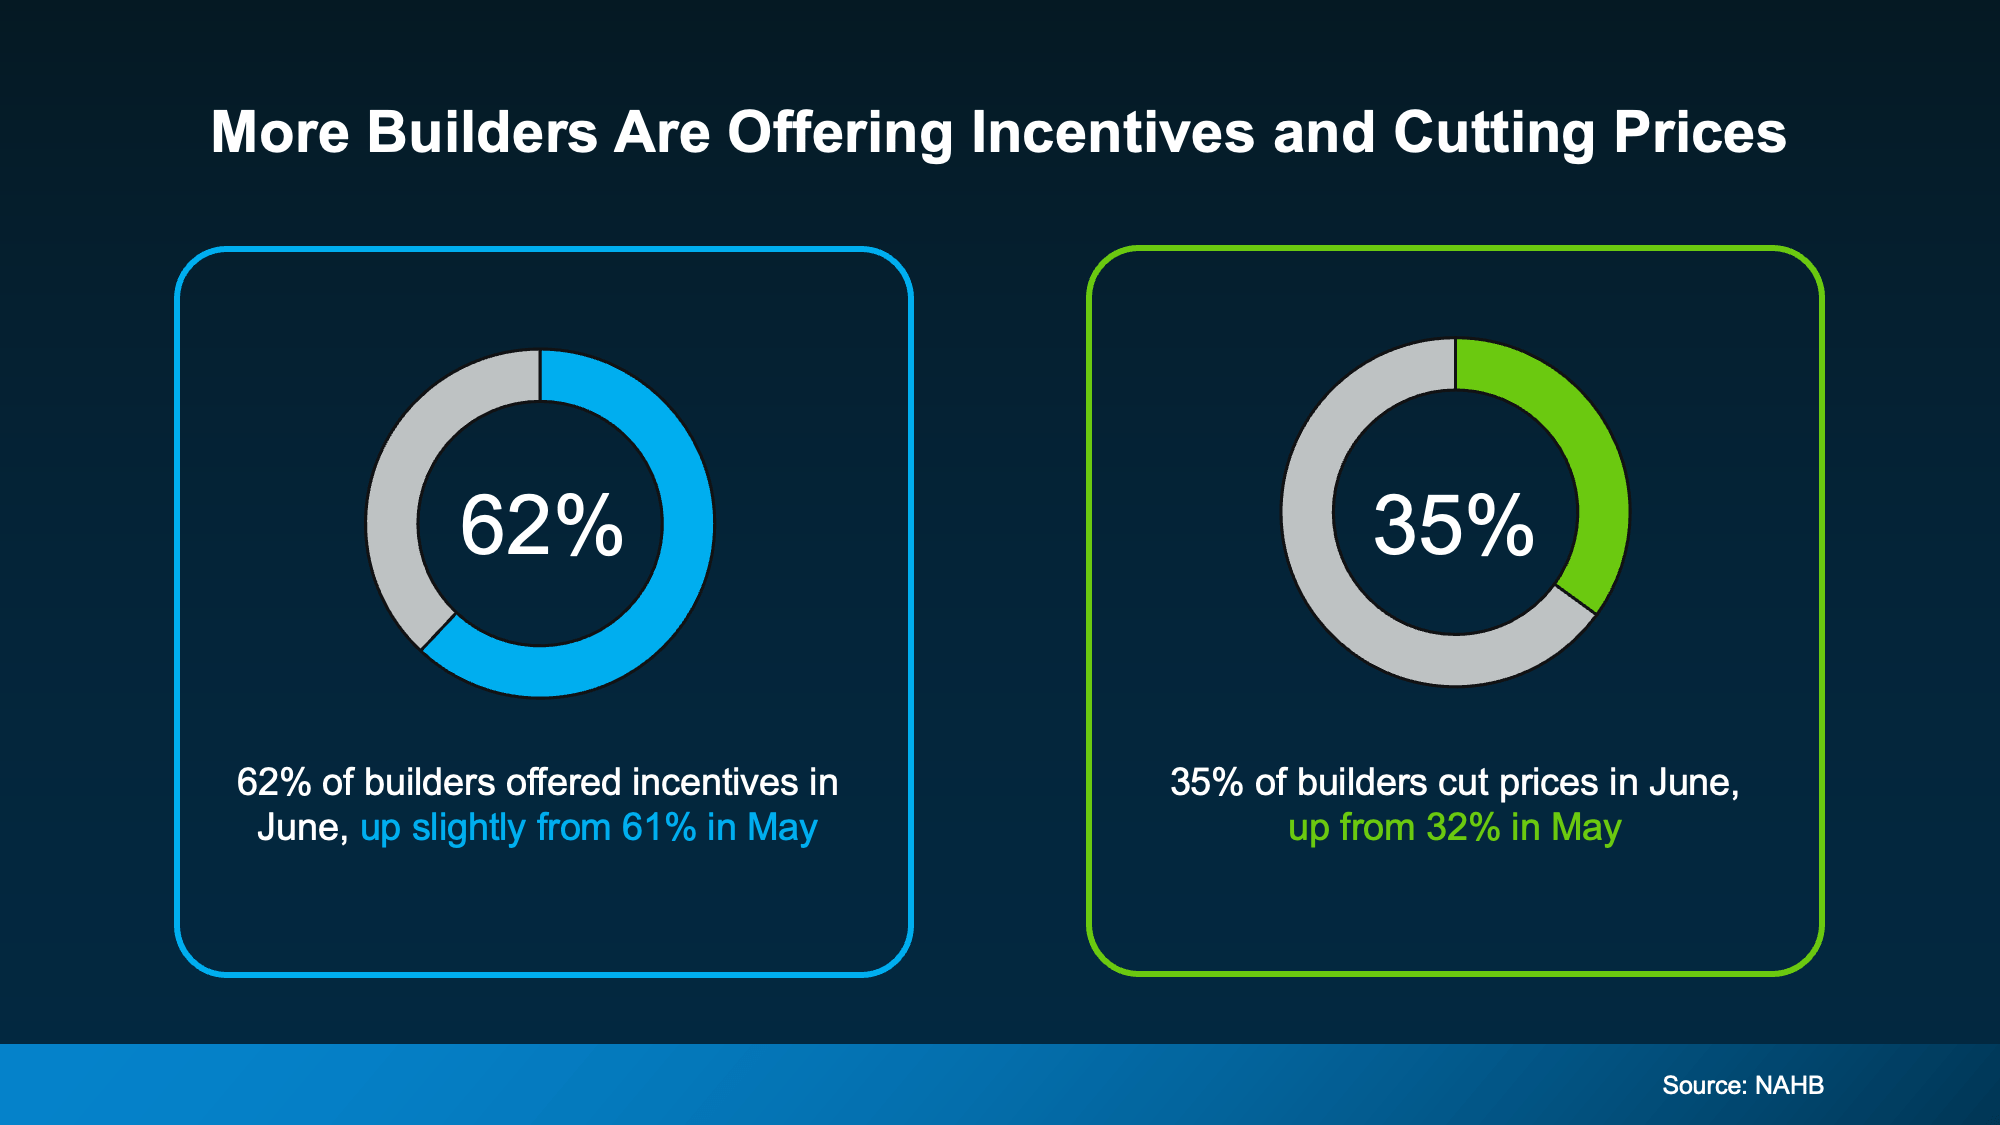
Newly built homes are seeing the same push and pull. According to the National Association of Home Builders (NAHB), 62% of builders are offering incentives right now. And about 35% are cutting prices outright (see chart below):

a screenshot of a graph

Those incentives often look like:

  • Price adjustments
  • Mortgage rate buydowns
  • Free upgrades, like nicer finishes or appliances

Danielle Hale, Chief Economist at Realtor.com, explains why:

“New construction has been one of the steadiest parts of the housing market over the past few years, but builders are clearly responding to today’s affordability pressures and higher levels of existing-home inventory.”

Even builders, who many people think rarely negotiate, are competing on price and perks. They have been for over a year now. The same data shows this is the 15th straight month where more than 60% of builders have offered incentives to sweeten the deal. And that’s significant.

What This Means for Your Move

If you’re buying, this is a good time to ask. Whether you have your eye on an existing house or a newly built home, there’s a chance the seller or builder will meet you partway on price, terms, or both.

If you’re selling, expect buyers to ask. Even builders of brand-new homes are making concessions more often than not right now. Holding firm on every term could mean more time on the market, or a lost sale altogether.

Bottom Line

Sellers and builders are both giving buyers more to work with this year. Want to know what’s realistic to expect in concessions and incentives in our market? Let’s connect.